Meaning, Requisites of Management Reporting

The reporting to management is a process of providing information to various levels of management so as to enable in judging the effectiveness of their responsibility centres and become a base for taking corrective measures, if necessary.

Meaning of Reporting:

The term “reporting” mean different things as follows:

(a) Narrating some facts

(b) Reviewing certain matter with its merits and demerits and offering comments

(c) Furnishing data at regular intervals in standardized forms

(d) Submitting specific information for particular purpose upon specific request instruction.

Management reporting refers to the formal system whereby relevant required information is furnished to management by means of reports constantly. Thus ‘report’ is the essence of any manage­ment reporting system.

The term ‘Report’ normally refers to a formal communication, which moves upwards, i.e., for factual communication by a lower level to a higher level of authority in response to orders received from higher level. Reports provide the means of checking the performance. A person, who is issued with orders or instructions to do certain things, should report back what he has done in compliance thereof. Reports may be oral or written and also routine or special.

Objectives or Purpose of Reporting to management

A Management Accountant has to prepare the report for the following purposes.

  1. Means of Communication: A report is used as a means of upward communication. A report is prepared and submitted to someone who needs that information for carrying out functions of management.
  2. Satisfy Interested Parties: The interested parties of management report are top management executives, government agencies, shareholders, creditors, customers and general public. Different types of management reports are prepared to satisfy above mentioned interested parties.
  3. Serve as a Record: Reports provide valuable and important records for reference in the future. As the facts and investigations are recorded with utmost care, they become a rich source of information for the future.
  4. Legal Requirements: Some reports are prepared to satisfy the legal requirements. The annual reports of company accounts is prepared to furnished the same to the shareholders of the company under Companies Act 1946. Likewise, audit report of the company accounts is submitted before the income tax authorities under Income Tax Act 1961.
  5. Develop Public Relations: Reports of general progress of business and utilization of national resources are prepared and presented before the public. It is useful for increasing the goodwill of the company and developing public relations.
  6. Basis to Measure Performance: The performance of each employee is prepared in a report form. In some cases, group or department performance is prepared in a report form. The individual performance report is used for promotion and incentives. The group performance report is used for giving bonus.
  7. Control: Reports are the basis of control process. On the basis of reports, actions are initiated and instructions are given to improve the performance.

Requisites of a Good Reporting System:

A good reporting system is a better guide and effective tool for efficient managerial decision ­making.

Hence, the essentials of a good reporting system are as follows:

  1. Proper Form:

In order to facilitate decision-making the information supplied should be in proper form. The style and layout of a report depend upon the needs of the individual who will use the same. The report may be submitted in the form of narration [written statement of facts], statisti­cal tabulations, graphs, charts, etc.

  1. Proper Time:

Promptness is very important because information delayed is information denied. Reports are meant for action and when adverse tendencies or events are noticed, actions should follow forthwith. The sooner the report is made, the quicker the corrective action be taken.

  1. Proper Flow of Information:

The information should flow from the right level of authority to the level of authority where the decisions are to be made. Further complete and consistent infor­mation should flow in a systematic manner.

  1. Flexibility:

The system should be capable of being adjusted according to the requirements of the user. For example, production manager should be provided with information relating to his division or area of control only.

  1. Facilitation of Evaluation:

The system should distinctively report deviations from standards or estimates. Controllable factors should be distinguished from non-controllable factors and re­ported separately. A good reporting system should give information required for the evaluation of each manager’s area of responsibility in relation to the goals of the organization.

  1. Economy:

There is a cost for rendering information and such cost should be compared with benefits derived from the report or loss sustained by not having the report. Economy is an informa­tion aspect to be considered while developing reporting system.

Purpose of Reporting for Management:

The reports serve the following purposes:

(a) Communication Mode:

The basic object of preparation of reports for reporting purposes is to facilitate upward communication. Through reports someone who has some information communicates to higher authority who needs that information for carrying out various functions of management.

Reports serve as a communication mode to communicate relevant information to management executives, government agencies, shareholders, creditors, suppliers, customers or general public. Reports also communicate authentic information to research scholars who are interested in collecting data information for various research matters. Hence reports can be considered most effective communication mode.

(b) Helpful in Record Keeping:

Reports also facilitate record keeping function. Since reports provide valuable and authentic records for future references. Reports usually include facts and findings of investigations which can be stored as valuable information. These stored facts can be of great importance in future.

(c) Meeting Legal Requirements:

Some of the reports are also prepared and submitted to fulfill legal requirements. For instance, annual report of company’s accounts is necessary to be furnished to the shareholders under Companies Act 1956. Similarly, audit report of accounts must accompany the Income tax return under Income tax Act, 1961, Interim reports are submitted quarterly as per clause 41 of listing agreement.

(d) Provides Basis for Taking Important Decisions:

Reports usually contain factual information related with some event. Reports kept as a valuable record also help management in providing basis for taking important decision. For instance salesman’s report and dealers report will provide basis for taking any decision related with sales matters.

(e) Develop Public Relations:

Sometimes reports are also written and submitted presenting information of general progress of business and utilization of national resources. These reports are usually available for general public and help in enhancing goodwill of the reporting entity and hence in developing public relations.

(f) Provide Basis to Measure Performance:

Routine reports about the work performance of employees help the management to measure performance in view of the objects. The reports on performance of employees shall also become basis for promotions and incentives.

(g) Facilitates Control:

Reports also facilitate control process in the organisation. Reports provide a relevant basis of any control process. In normal course of the business, it is on the basis of reports, actions are initiated and instructions are given to improve the performance.

(h) Feedback:

Reports also help the lower levels in providing feedback to the management in form of reactions on decisions taken by the management.

Author and Reece have rightly said, “Reports on what has happened in a business, are useful for two general purposes which may be called information and control respectively.”

So information reports are useful to tell management what is going on. Control reports on the other hand, are useful in assessing personal performance and economic performance.

(i) Help in Combating Changes:

Since business itself is dynamic one, business conditions keep on changing, they pose a serious challenge to the existence of a corporate entity. Reports aim at analyzing the impact of business dynamics and how best changes can be exploited to the benefit of the company.

(j) Facilitates Coordination:

Reporting also helps in coordinating the activities in an organisation. The act of coordinating can be best performed with the help of various reports.

(k) Contact with Users:

Reports act as a mean to remain in touch with consumers, suppliers, shareholders and Government agencies.
Principles of Good Reporting System

A good reporting system helps the management in proper planning and controlling. If the reports are available to every level of management at the proper time, current activities may be regulated and controlled and necessary corrective actions may also be taken in time. Hence, some principles have been followed for making the reporting system more effective. Such principles are briefly explained below.

General Principles of Reporting System

  1. Proper Flow of Information: The information should be free flow from the proper place to the right end user of the report. Hence, the information should be presented in the right format and at a proper time so that it helps in planning and co-ordination. The flow of report should not be delayed at any cost. Flow of information is a continuous activity. Information may flow upward, downward or sideways within an organization. Orders, instructions, plans etc may flow from top to bottom. Reports of grievances, suggestions etc. may flow from bottom to top. Notifications, letters, settlements and complaints may flow from outside. Annual Report, Financial Statement Analysis Report, Directors Report, Auditors report etc. may flow from inside to outside. Information flows as sideways from one manager to another at the same level through meetings, discussion etc.
  2. Proper Timing: The very purpose of preparation of report is controlling the unfavorable activities. Hence, the report should be submitted at the required time at any cost. If not so, there is no use of preparing such report. Moreover, the efforts used for preparing the report and time are also waste. In the case of routine report, the time schedule should be strictly adhered to. The absence of information at required time leads to taking wrong decision.
  3. Accurate Information: The report contains only accurate information. If wrong information are included in the report, it may lead to take wrong decision. Hence, the supply of accurate information helps the managerial executives to understand the situation very clearly. At the same time, the presentation of accurate information in the report should not involve excessive cost of preparation and should not result in the delay in the presentation of report.
  4. Relevant Information: Proper attention should be devoted to include only relevant information in the report. The inclusion of irrelevant information is waste one and increase the time in the report preparation. Moreover, the irrelevant information confuse the end user of the report.
  5. Basis of Comparison: The information bestowed by reports will be helpful when it carries provision to compare with past figures, standards set or objectives. The trend of the variation can be find out only through the comparison. Corrective action can be taken with the help of comparative information.
  6. Reports should be Clear and Simple: The very purpose of preparing a report is helping the management in planning, coordinating and controlling. Hence, the report should be presented in very simple terms and can be clearly understood by anybody. If not so, there is no meaning of preparing a report. The method of presenting a report is in such a way that attracts the eye of the readers and enables them to arrive at a conclusion. The arrangement of information in a report is in brief, complete, clear and simple.
  7. Cost: The management incur some expenses with regard to report preparation. Such expenses should be commensurate with the benefits derived from the report preparation. If possible, more benefits may be available than the expenses incurred. In this way, reporting system can be installed. In other words, there should be an endeavor to make the system as economical as possible.
  8. Evaluation of Responsibility: The reporting system has been installed in such a way to evaluate the managerial responsibility. The standards or targets are fixed for each functional department. The record of actual performance is monitored along with the standards so as to enable management to assess the performance of different individuals.
  9. Factual: A good reporting system should be based on reports containing factual information’s. Management has to take decision in future on the basis of the information contained in various reports. Any false information contained in the reports will not be helpful in taking correct decisions.
  10. Principle of Brevity: Principle of brevity should be followed while reporting since long reports are very difficult to analyze and long reports generally rely greatly on highlighting irrelevant minor details and major issues involved are not taken up properly.
  11. Principle of Scheduling: Principle of scheduling should also be followed in a way that reports can be prepared without excess burden on the staff. Employees must be given sufficient time to do the work well on the preparation of report. Time lag between collection of data and finished report should not be much longer.

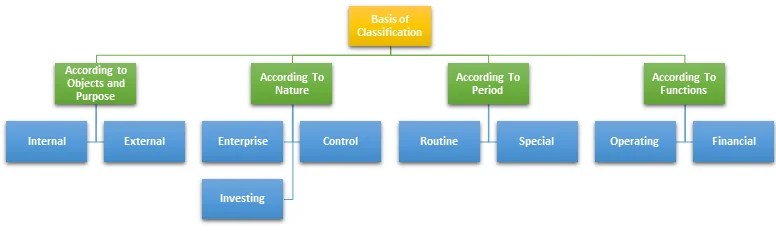
Kinds of Management Reports

  1. Classification on the Basis of Object and Purpose:

(a) External Reports:

The reports prepared for external users or for the persons outside the business are known as external reports. External users may include shareholders, investors, creditors, suppliers and bankers. Though company may not be answerable to outsiders but still some reports are meant for outsiders.

The company publishes income statement and balance sheet at the end of every financial year and these statements are filed with the Registrar of companies and stock exchanges. Final statements of accounts are expected to conform to certain basic details in India Companies Act 1956 has made it obligatory to disclose some minimum information in final accounts. Following is an instance of Balance

(b) Internal Reports:

Internal reports refers to those reports which are meant for different level of management. Internal reports are not public documents and they are not expected to conform to any standards. These reports are prepared by keeping in view the needs of disposal for scanning them.

These reports may be meant for top level, middle level and lower level. The report meant for different levels of management may be regarded as internal reports. The frequency of these reports vary in accordance with purpose they serve.

Some of the internal reports that are commonly used are! Period report about profit and loss account and financial position, statement of cash flow, changes in working capital, report about cost of production, production trends and utilization of capacity.Labour turnover reports, material utilization reports, periodic reports on sales, credit collection periods and selling and distribution expenses, report on stock position etc.

2. Classification on the Basis of Nature:

According to nature, reports can be classified into three categories:

(a) Enterprise Reports:

These reports are prepared for the concern as a whole. These reports serve as a channel of communication with outsiders. Enterprise reports may concern all activities of the enterprise or may be related to different activities. Enterprise reports may include balance sheet, income statement, income tax returns, employment report, chairman’s report.

These reports contain standardized information and are beneficial to outsiders. The interpretation of financial statement can also be undertaken from these reports. The reports are important from financial analysis point of view. For instance following is chairman’s report presented by ShashiRuia Chairman of Essar Steel Ltd. reproduced for information:

Chairman’s Statement:

Dear Shareholder,

It is now well accepted by economic pundits and studies conducted across the globe that India and China will dominate the world economy in the 21st century. India is today the fourth largest economy in terms of purchasing power parity and is expected to overtake Japan and become third largest economic power after the United States of America and China, before the end of the decade. As India prepares to become an economic super power, it must further quicken the pace of reform and liaberalization by enabling the development of world class infrastructure, competitive manufacturing in scale and technology and sustainable development.

GDP growth of over 6.5% significant investments in infrastructure, a good agricultural output and a spurt in consumer demand across all sectors augurs for industry. If we are able to achieve a GDP growth of 8% annually, India will be the fastest growing free market democracy in the world.

Steel the backbone of Industry:

The steel industry is crucial to a nation’s economic competitiveness and security. Steel is integral to building of bridges, railroads, homes, automobiles, appliances and much more. Today’s steels are radically different than what was available ten years ago. They are lighter, higher in strength and more versatile.

The industry has undergone a major transformation in the last few years with companies investing in new process and product technologies, capacity enhancements and customer service initiatives. Indian steel companies are at the ‘leading edge’ of technology and spend considerable amounts on research and development.

The industry and particularly your company are able to compete internationally on technology, quality and price and have demonstrated that the India of tomorrow belongs to Indian entrepreneurs and Indian consumers. The Government needs to encourage and support the industry with a more realistic iron ore policy that creates level playing field.

Essar Steel- an eventful year:

Essar Steel’s excellent results demonstrate the company’s success in structurally improving its operating performance as a result of strategic actions and timely execution of projects. We have seen some signs of over-supply in international markets, but we do not see this as a long term issue. Your company is also much better prepared to manage cyclically in markets due to its geographic coverage and product portfolio.

Essar Steel is now a fully integrated producer with end-to-end control of all operations related to steel making. The acquisition of Hy-Grade Pellets Ltd. and Steel Corporation of Gujarat Ltd. make your company a totally integrated steel producer. The company has taken a number of initiatives in its manufacturing facilities to fulfill its mission of being one of the most cost efficient producers of steel globally.

From Bailadilla- where the iron ore beneficiation plant is located, close to the iron mines- to the final stage where the end products are dispatched to domestic and international destinations, your company has ensured that every stage of manufacture is seamlessly integrated. This will enable us to offer high quality, customized products for use by wide range of industries such as automobile and auto components, white goods, construction and consumer durables.

We focus on value addition at every stage of manufacture and also direct our efforts to high revenue generating markets. We do this by targeted marketing in specialized customer segments and technical and aftermarket support. We expect these value added products to contribute over 35% of the company’s revenues in the coming year.

Looking Ahead:

Currently we are producing at a capacity of 3 million tonnes and we have planned to augment this to 4.6 million tonnes by June 2006, making us the largest producer of flat steel in the private sector in India. This will involve an incremental investment ofRs 2000 crore, which is much below industry average and will considerably reduce our cost of production. We also plan to increase the pellet making capacity at Visakhapatnam from 4 to 8 million tonnes in this fiscal year.

The acquisitions, capacity expansions, technology upgradation and other productivity improvement measures will give you company a significant competitive edge in domestic and international markets. Our thrust on maintaining cost leadership through integrated manufacturing processes, research and new innovation and high productivity will provide a hedge against cyclically.

Managing Financial Turnaround:

Your company has been able to build a platform for consolidation and sustain the rejuvenation of its performance. In October 2002, at the time of the announcement of the CDR package, the Company had a term debt of? 5371 crore, which has been reduced to Rs 4262 crore as at March 31, 2005, a reduction of over Rs 1100 crore. The significant financial turnaround by the Company in such a short period of time is indeed noteworthy. With all other parameters of financial performance showing considerable improvement, your company is in a much stronger position to plan for more aggressive growth.

Our Driving Force:

Essar Steel is today at a significant point in its history. The past has given us learning’s that we have used to build a platform of security from the future. I must acknowledge the tremendous efforts put in by employees at all levels, who have to admirably risen to the challenges that change inevitably brings. Organizations must continuously change in order to survive and prosper. The Essar family has shown the capability and resilience to manage this change. We look to the future with confidence that arises out of our actions and the achievements of our people, as we prepare to face the “Brave New World”.

I also take this opportunity to thank our customers, vendors, business associates and bankers who have helped us come this far and look forward to their continued support in our journey to globalization.

Thank You.

ShashiRuia Chairman

(b) Control Reports:

Control reports deal with two aspects. One aspect relates to the personal performance and the other aspect deals with the economic performance. The first type of reports are prepared and reported to judge performance of managers and heads of various responsibility centres with what performance should have been under the prevailing circumstances.

The reasons for deviations in performance are also identified. The second type of reports shows how well the responsibility centre has fared as an economic activity. Such analysis is made periodically. This type of analysis requires the use of full cost accounting rather than responsibility accounting.

Control reports should consider the following:

(i) Control reports should be related to personal responsibility.

(ii) They should compare actual performance with the standards.

(iii) They should highlight significant information.

(iv) These reports should be sent at a proper time as to enable taking corrective measures.

(v) If possible various accounting ratios like, capacity, efficiency, activity and calendar ratios may be calculated.

(c) Investigating Reports:

These reports are linked with control reports. In case some serious problem arises then the causes of this situation are studied and analyzed, investigative reports are based on outcome of special solution studies. These reports are intermittent and are prepared only when a situation arises. They are prepared according to the nature of every situation. They are helpful to the management in analyzing the causes of some problem.

Example of Investigating Report:

The following information is available from monthly cost report of M/s Hard Engineering Co.:—

3. Classification on the Basis of Period:

According to the period repots can be classified as under:

(a) Routine Reports:

These reports are prepared about day to day working of the concern. They are periodically sent to various levels of management. These persons may differ according to the nature of information about details to be reported so far as the timing is concerned they may be sent daily, weekly, monthly or quarterly.

Routine reports may relate to sales information, production figures, capital expenditures, purchases of raw materials, market trends etc. There is a tendency to ignore routine reports by all recipients because of their routine nature. Important information in the report should be high-lighted or presented in a different way or may be written in a different ink.

Example of two routine reports are:

  1. Statement of Production
  2. Statement of Expenses

(b) Special Reports:

The management may confront some difficulties and routine report may not give sufficient information to tackle such situations. Under such circumstances, special reports are called for. Special reports are required for special purposes only.

These reports are prepared according to the need of situation. Available accounting information may not be sufficient, so data may have to be specially collected. There may be need to put extra staff for compiling these reports. It may also involve co-ordination of different departments and different levels of management. According to J. Batty33 special reports should be divided into sections each covering the following main purposes: 1. Reason for the report 2. Investigation made 3. Finding a conclusion and recommendations.

Special reports may deal with following topics:

(i) Information about market analysis and methods of distribution of competitors.

(ii) Technological changes in industry.

(iii) Problems about the purchase of materials.

(iv) Reports about change in methods of production and their implications.

(v) Trade association matters.

(vi) Report by secretary on company matters.

(vii) Political development at home and abroad having impact on business.

(ix) Report effect of idle capacity on cost of production.

(x) Make or buy decisions.

(xi) Report most suitable method of raising funds.

(xii) The effect of labour disputes on production and cost of production.

(xiii) Report on general economic forecast.

(xiv) Feasibility study for a project.

(xv) Report on effect of change in Government Policy.

4. Classification of Reports on the Basis of Functions:

According to function the reports may be divided into two categories:

(a) Operating Reports

(b) Financial Reports

(a) Operating Reports:

These reports provide information about operations of the concern.

The operating reports may consist of the following:

(i) Control Reports:

These reports are used for management control purposes. They are intended to spot deviations from budgeted performance without loss of time so that corrective action can be taken. Control reports are also used to assess the performance of individuals.

(ii) Information Reports:

These reports are prepared to provide useful information which will enable planning and policy formation for future. Information reports can take the form of trend reports and analytical reports. Trend reports provide information in comparative form over a period of time. Graphic presentation can be effectively used in trend reports. As opposed to trend reports, analytical reports provide information in a classified manner about composition of certain results so that one can identify specific factors in the overall total.

(b) Financial Reports:

These reports provide information about the financial position of the concern on specific dates or movement of finances during a specific period. The Balance Sheet provides information about a concern on a specific date. On the other hand Cash Flow Statement provides data about the movement of cash during a particular period. These reports can be either static or dynamic. Balance Sheet and other subsidiary reports are examples of static reports; Cash Flow, Fund Flow Statements and other reports showing financial position as compared to the budgeted are examples of dynamic reports.

Limitations of Cash Flow Statement

  • A Cash Flow Statement only reveals the inflow and outflow of cash. The cash balance disclosed by this statement may not depict the true liquid position. There are controversies over a number of items like Cheques, stamps, postal orders etc. to be included in cash.
  • A Cash Flow Statement cannot be equated with the income statement. An income statement takes into account both cash and non-cash items. Hence Cash Fund does not mean net income of the business.
  • Working Capital being a wider concept of funds, a funds flow statement presents a more complete picture than cash flow statement.
  • Fails to Present Net Profit: The cash flow statement fails to present the net income of a firm for the period as it ignores non-cash items which are considered by Profit and Loss Statement. The cash flow statement does not help to assess profitability as it neither considers cost nor revenues. However, it can be used as a supplement to the income statement.
  • Not a substitute to Funds Flow Statement or Income Statement: The functions which are performed by funds flow statement or income statement cannot be done by cash flow statement.
  • Industry Comparison not possible: As the cash flow statement does not measure the efficiency of the firm, intercomparison with other inter-industry is not possible. A firm having less capital investment shall have less cash flow than the firm which more capital investment resulting in higher cash flows.
  • Does not Properly Assess Liquidity position: In a practical scenario, the cash flow statement does not assess liquidity or solvency position of the firm as it presents cash position only on a particular date. It only helps to know what amount of obligation can be met. In nutshell, it does not represent the real liquidity position.
  • It does not give complete picture of the financial position of the business concern.
  • The preparation of cash flow statement is only postmortem analysis. There is no projection of cash in future in this method.
  • It is not a substitute of Income Statement.
  • The accuracy of cash flow statement is based on the balance sheet. If balance sheet is wrong, the cash flow statement is also wrong.
  • It is not prepared on the basic accounting concept of accrual basis. Hence, the accuracy of cash flow statement is questionable.
  • It is not suitable for judging the profitability of a firm as non-cash items are not included in the calculation of cash flow from operating activities.

Uses of Cash Flow Statement

The purpose of the cash flow statement is to show where an entities cash is being generated (cash inflows), and where its cash is being spent (cash outflows), over a specific period of time (usually quarterly and annually). It is important for analyzing the liquidity and long term solvency of a company.

The cash flow statement uses cash basis accounting instead of accrual basis accounting which is used for the balance sheet and income statement by most companies. This is important because a company may accrue accounting revenues but may not actually receive the cash. This could produce profits and taxes payable but not provide the resources to stay solvent.

Cash Flow Statement Components

The cash flow statement components provide a detailed view of cash flow from operations, investing, and financing:

Cash Flow from Operating Activities

The net amount of cash coming in or leaving from the day to day business operations of an entity is called Cash Flow from Operations. Basically it is the operating income plus non-cash items such as depreciation added. Since accounting profits are reduced by non-cash items (i.e. depreciation and amortization) they must be added back to accounting profits to calculate cash flow.

Cash flow from operations is an important measurement because it tells the analyst about the viability of an entities current business plan and operations. In the long run, cash flow from operations must be cash inflows in order for an entity to be solvent and provide for the normal outflows from investing and finance activities.

Cash Flow from Investing Activities

Cash flow from investing activities would include the outflow of cash for long term assets such as land, buildings, equipment, etc., and the inflows from the sale of assets, businesses, securities, etc. Most cash flow investing activities are cash out flows because most entities make long term investments for operations and future growth.

Cash Flow from Finance Activities

Cash flow from finance activities is the cash out flow to the entities investors (i.e. interest to bondholders) and shareholders (i.e. dividends and stock buybacks) and cash inflows from sales of bonds or issuance of stock equity. Most cash flow finance activities are cash outflows since most entities only issue bonds and stocks occasionally.

Main uses of cash flow statement.

  • Since a cash flow statement is based on the cash basis of accounting, it is very useful in the evaluation of cash position of a firm.
  • A projected cash flow statement can be prepared in order to know the future cash position of a concern so as to enable a firm to plan and coordinate its financial operations properly. By preparing this statement, a firm can come to know as to how much cash will be generated into the firm and how much cash will be needed to make various payments and hence the firm can well plan to arrange for the future requirements of cash.
  • A comparison of the historical and projected cash flow statements can be made so as to find the variations and deficiency or otherwise in the performance so as to enable the firm to take immediate and effective action.
  • A series of intra-firm and inter-firm cash flow statements reveals whether the firm’s liquidity (short-term paying capacity) is improving or deteriorating over a period of time and in comparison to other firms over a given period of time.
  • Cash flow statement helps in planning the repayment of loans, replacement of fixed assets and other similar long-term planning of cash. It is also significant for capital budgeting decisions.
  • It better explains the causes for poor cash position in spite of substantial profits in a firm by throwing light on various applications of cash made by the firm. It further helps in answering some intricate questions like -what happened to the net profits? Where did the profits go? Why more dividends could not be paid in spite of sufficient available profit?
  • Cash flow analysis is more useful and appropriate than funds flow analysis for short-term financial analysis as in a very short period it is cash which is more elevant then the working capital for forecasting the ability of the firm to meet its immediate obligations.
  • Cash flow statement prepared according to AS-3 (Revised) is more suitable for making comparisons than the funds flow statement as there is no standard format used for the same.
  • Cash flow statement provides information of all activities classified under operating, investing and financing activities. The funds statement even when prepared on cash basis, did not disclose cash flows from such activities separately. Thus, cash flow statement is more useful than the funds statement.

Statement of Funds from Operations

Funds from operations is the cash flows generated by the operations of a business, usually a real estate investment trust (REIT). This measure is commonly used to judge the operational performance of REITs, especially in regard to investing in them. Funds from operations does not include any financing-related cash flows, such as interest income or interest expense. It also does not include any gains or losses from the disposition of assets, or any depreciation or amortization of fixed assets. Thus, the calculation of funds from operations is:

Funds from operations = Net income – Interest income + Interest expense + Depreciation – Gains on asset sales + Losses on asset sales

After preparing the schedule of changes in net working capital, the second step is to determine the amount of funds (loss) from business operations. It refers to the funds or loss, which is generated or suffered in the business as a result of its regular operations during the period. The funds from operation is an important source of fund, while loss from operation is one of the important applications of funds. The funds or loss from operation is determined by adjusting the firm’s net income in a statement called the statement of funds from operations. In this statement, the items such as non-operating incomes and non-cash expenses are adjusted while determining the amount of funds (loss) from operations.

Non-cash expenses such as depreciation and amortization of intangible assets do not result in actual cash outflow. Non-operating expenses are those which are not treated as regular expenses of the business. These expenses matter while ascertaining the business income, but are irrelevant in determining the funds (loss) from operations. Therefore non-operating incomes should be deducted from and non-operating and non-cash expenses should be added back to the business income shown by the income statement.

Non-operating and non-cash expenses

  • Depreciation for the year
  • Amortization of Goodwill, Copyright, Patent, Trademark, Preliminary expenses
  • Discount on issue of share and debenture written off
  • Loss on sale of fixed assets or investment
  • Loss of revaluation of fixed assets
  • Premium on redemption of debentures and preference share

Incomes and gains which are not earned from the normal business operations are called non-operating incomes. These incomes are included while ascertaining the business income, but are excluded while determining the funds (loss)from operations. The following are the examples of non-operating incomes.

  • Gain on sale of fixed assets or investment
  • gain on revaluation of fixed assets
  • Discount on redemption of debentures and preference share
  • Compensation received
  • Interest received
  • Refund of tax
  • Transfer fees received
  • Appreciation on fixed assets

Preparation of Statement Of Funds From Operation

Funds from operations can be determined by using one of the two following methods.

  1. Add Back Method

Under this method,net profit is taken as the base. All the non-operating and non-cash expenses are added to net profit and non-operating incomes are deducted.

Funds from operations = Net profit+Non-operating and non-cash expenses-Non operating Incomes.

  1. Profit And Loss Adjustment Account Method

Funds from operations can also be determined by preparing an account called profit and loss adjustment account begins with opening balance of profit on its credit side and closing balance on the debit side. Instead of opening and closing balance of profit and loss account, only the amount of net profit for the year can also be brought down to the debit side of this account. Then the items of non-operating expenses and non-cash expenses are adjusted to the debit side and the items of non-operating incomes are adjusted to the credit side to determine the amount of funds (loss) from operations.

Statement of Sources and Applications of Funds

Generally, the statement consists of two sections: the source (where the money has come from) and the application (where the money has gone).

The sources of funds originate from:

  • A decrease in liabilities or an increase in assets
  • Net income after tax
  • The disposal or revaluation of fixed assets
  • Proceeds of loans obtained
  • Proceeds of shares that were issued
  • Repayments received on loans previously granted by the company
  • Any increase in net working capital

The application of funds includes:

  • Losses to be met by the company
  • The purchase of fixed assets/investments
  • The full or partial payment of loans
  • Granting of loans
  • Liability for taxes
  • Dividends paid or proposed
  • Any decrease in net working capital

Sources of Funds

Items to be shown under the head Sources of Funds are as follows:

  • Issue of Shares and Debentures for Cash: The total amount received from the Issue of Shares or Debentures is to shown under this head. But, the Issue of bonus Shares or Conversion of Debentures into Equity Shares or Shares issued to vendors shall not be shown here as there is no inflow of Cash
  • Long Term Loans: The Amount received on raising Long Term Loans is shown under this head. Short Term Loans are not to be shown here as their treatment has already been done while preparing the Statement of Changes in Working Capital.
  • Sale of Investments and other Fixed Assets: The Total Amount received on the sale of Investments and other Fixed Assets is to be shown under this head.
  • Funds from Operations: The Funds generated from Operations as computed in Step II are also required to be shown here.
  • Decrease in Working Capital: This would be the Balancing Figure of the Statement and will come from change in Working Capital Statement

Application of Funds

Items to be shown under Application of Funds are as follows:

  • Purchase of Fixed Assets and Investments: The Cash Payment made for purchase of Fixed Assets and Investments is an application of Funds. But if the purchase if made by issue of shares or debentures, such a transaction will not constitute application of funds. Similarly, if the purchases are on credit, these will not constitute fund applications.
  • Redemption of Debentures, Preference Shares and Repayment of Loan: Payment made including Premium (less: Discount) is to be taken as fund application
  • Payment of Dividend & Tax: Payment of Dividend and Tax are to be taken as applications of fund if the provisions are excluded from Current Liabilities and Current Provisions are added back to profit to determine the “Funds from Operations”
  • Increase in Working Capital: This would be the Balancing Figure of the Statement and will come from change in Working Capital Statement

Procedure for preparation of Fund Flow Statement

Steps for Preparing Funds Flow Statement:

The steps involved in preparing the statement are as follows:

  1. Determine the change (increase or decrease) in working capital.
  2. Determine the adjustments account to be made to net income.
  3. For each non-current account on the balance sheet, establish the increase or decrease in that account. Analyze the change to decide whether it is a source (increase) or use (decrease) of working capital.
  4. Be sure the total of all sources including those from operations minus the total of all uses equals the change found in working capital in Step 1.

General Rules for Preparing Funds Flow Statement:

The following general rules should be observed while preparing funds flow statement:

  1. Increase in a current asset means increase (plus) in working capital.
  2. Decrease in a current asset means decrease (minus) in working capital.
  3. Increase in a current liability means decrease (minus) in working capital.
  4. Decrease in a current liability means increase (plus) in working capital.
  5. Increase in current asset and increase in current liability does not affect working capital.
  6. Decrease in current asset and decrease in current liability does not affect working capital.
  7. Changes in fixed (non-current) assets and fixed (non-current) liabilities affects working capital.

Format of Funds Flow Statement:

A funds flow statement can be prepared in statement form or ‘T’ form.

Both the formats are given below:

Schedule of Changes in Working Capital:

Many business enterprises prefer to prepare another statement, known as schedule of changes in working capital, while preparing a funds flow statement, on a working capital basis. This schedule of changes in working capital provides information concerning the changes in each individual current assets and current liabilities accounts (items).

This schedule is a part of the funds flow statement and increase (decrease) in working capital indicated by the schedule of changes in working capital will be equal to the amount of changes in working capital as found by funds flow statement. The schedule of changes in working capital can be prepared by comparing the current assets and current liabilities at two periods.

The format of schedule of changes in working capital is as follows:

Statement of changes in Working Capital

In the preparation of funds flow statement, the first step is to find out the net amount of increase or decrease of working capital, as increase in net working capital is a use of funds and decrease in net working capital is a source. Since net working capital is excess of current assets over current liabilities, the increase or decrease in the net working capital can be found out by comparing the current assets and current liabilities contained in the balance sheets of two following dates. For this purpose, a statement is prepared which is called statement or schedule of changes in net working capital. This statement helps to identify the change in position of the working capital. While preparing the statement of changes in working capital, the following points are considered.

* Increase in current assets , increase in net working capital
* Decrease in current assets , decrease in net working capital
* Increase in current liabilities , decrease in net working capital
* Decrease in current liabilities, increase in net working capital

The statement or schedule of changes in net working capital can be prepared by using one of the following forms.

  1. Using only current account

The statement or schedule of changes in net working capital can be prepared by using only current account, viz. account of current assets and current liabilities. While preparing the statement, the current assets and current liabilities of the previous year are compared with those of the current year and changes (increase or decrease) therein are determined. If the total of increase is more than that of decrease, there is an increase in net working capital, or vice versa.

  1. Using both current and non-current accounts

The statement or schedule of changes in net working capital can also be prepared by using both current as well as non-current accounts. Current account is the account of current assets and current liabilities and non-current account of non-current assets and non-current liabilities and owner’s equity. Increase in an item of current assets or decrease in an item of current liabilities from previous year to this year is debited, while increase in an item of current liabilities or decrease in an item of current assets is credited to current account. On other hand, increase in an item of non-current assets or decrease in an item of non-current liabilities from the previous year to this year is debited, while increase in an item of non-current liabilities and owner’s equity and decrease in an item of non-current assets is credited to non-current account.

The preparation of statement of changes in networking capital under this method is advantageous as compared to the previous method as it is easy to prepare funds flow statement there from.

Changes in Net Working Capital = Working Capital (Current Year) – Working Capital (Previous Year)

Or

Change in a Net Working Capital = Change in Current Assets – Change in Current Liabilities

  • Step 1: Find the Current Assets for the current year and previous year

From the point of the current asset of view, we consider the below:

      • Inventory
      • Accounts Receivable
      • Prepaid Expenses
  • Step 2: Find the Current Liability for the Current Year and Previous Year

From the current liabilities, we consider the below:

      • Accounts Payable & Accrued Expenses
      • Interest Payable
      • Deferred Revenue
  • Step 3: Find Working Capital for the Current Year and Previous Year
      • Working Capital (Current Year) = Current Assets (current year) – Current Liabilities (current year)
      • Working Capital (Current Year) = Current Assets (current year) – Current Liabilities (current year)
  • Step 4: Calculate Changes in Net Working Capital using the formula below –
      • Changes in Net Working Capital Formula = Working Capital (Current Year) – Working Capital (Previous Year).

Uses and Limitations of Fund Flow Statement

Uses of Funds Flow Statement:

By highlighting the changes in the distribution of the resources of an undertaking, the funds flow statement enables the financial manager to have a clear perspective of the organization’s financial strengths and weaknesses. It provides answers to a number of difficult questions.

(a) It explains the financial consequences of business operations. For example, a business may be earning huge profits, but its liquidity position would be highly unsatisfactory.

The funds statement will explain the causes for such situation by showing what has become of the profits earned. Further, the statement would explain the direction of flow of funds into productive or non-productive activities.

When a balance sheet presents a distorted picture of an undertaking because of a number of non-fund transactions, the funds statement would be an illuminating document.

(b) Debt capital is very essential for increased profitability of any enterprise. But the creditors may like to ascertain the credit worthiness and the funds generating capacity of the organization.

They may like to know in what way the management has utilized the funds in the past and how the funds would be utilized in future. The funds flow statement would enable the finance manager to answer such questions in a befitting manner.

(c) It acts as an instrument for allocation of the company’s scarce resources. A proposed funds statement will help to find out how the management is going to allocate the resources for meeting future productive programmes of the business.

When the projected funds statement is tied to the capital budget, it will help management to maintain the financial health of the organization.

(d) It is a test for evaluating the effective use of working capital by the management. Information on the adequacy or inadequacy of working capital will enable the management to decide what possible steps it should take for effective use of surplus working capital, or in the case of inadequate working capital to make suitable arrangements to make up the deficiency.

Limitations of Funds Flow Statement:

Despite its multiple managerial uses, the funds flow statements suffer from certain limitations.

  1. As this statement ignores non-fund items, it becomes a crude device compared to the income statement and balance sheet.
  2. The statement does not reveal shifts among the items making up the current assets and current liabilities. It does not tell whether any loss of working capital has unduly weakened the financial position.

Only an examination of the balance sheet at the end of the period will show the end of these changes. Therefore, funds flow statement cannot supplant but only supplement the conventional financial statements, either in whole or in part.

  1. The information used for the preparation of funds flow statement is essentially historical in nature, though attempts are made to project the funds statement for the future period.

Despite these limitations, the information supplied by the funds flow statement is really an invaluable aid to management in planning capital expenditure, devising dividend and other financial policies.

error: Content is protected !!