Stakeholder engagement

Stakeholder engagement refers to the process of engaging with stakeholders in order to understand their perspectives, needs, and concerns, and to involve them in decision-making processes. Stakeholders can include a wide range of individuals and groups that are affected by a company’s operations, including customers, employees, suppliers, local communities, civil society organizations, and government regulators.

Effective stakeholder engagement is an important aspect of corporate social responsibility (CSR) and corporate governance. Engaging with stakeholders can help companies to build trust and credibility, identify and address social and environmental risks, and create value for all stakeholders.

There are several steps involved in stakeholder engagement:

  1. Identify stakeholders: Companies must first identify who their stakeholders are and determine how they are affected by the company’s operations. This can involve mapping stakeholders and their interests, concerns, and power.
  2. Understand stakeholder perspectives: Companies must then engage with stakeholders in order to understand their perspectives, needs, and concerns. This can involve conducting surveys, focus groups, and other forms of research.
  3. Involve stakeholders in decision-making: Companies should involve stakeholders in decision-making processes that affect them. This can involve holding public consultations, involving stakeholders in advisory committees, and other forms of engagement.
  4. Communicate with stakeholders: Companies should communicate regularly with stakeholders in order to keep them informed about the company’s activities and to address any concerns they may have. This can involve regular reporting, social media engagement, and other forms of communication.
  5. Monitor and evaluate: Companies should monitor and evaluate their stakeholder engagement activities in order to determine their effectiveness and identify areas for improvement.

Stakeholder engagement can bring a wide range of benefits to companies:

  1. Improved reputation: Engaging with stakeholders can help companies to build trust and credibility with the public, investors, and other stakeholders. This can help to enhance the company’s reputation and brand value.
  2. Better decision-making: By involving stakeholders in decision-making processes, companies can gain valuable insights and perspectives that can help them to make better decisions. This can lead to better outcomes for the company and its stakeholders.
  3. Enhanced risk management: Engaging with stakeholders can help companies to identify and address social and environmental risks, as well as emerging trends and issues that may impact the company’s operations. This can help to reduce the company’s exposure to risk and improve its resilience.
  4. Innovation and creativity: By involving stakeholders in the innovation process, companies can tap into a wide range of ideas and perspectives that can help to drive innovation and creativity.
  5. Improved employee morale: Engaging with employees as stakeholders can help to improve their morale and job satisfaction, which can lead to higher levels of productivity and retention.
  6. Better relationships with suppliers: Engaging with suppliers as stakeholders can help to build stronger relationships, improve supply chain transparency, and promote responsible sourcing practices.
  7. Improved financial performance: By building trust with stakeholders and addressing social and environmental risks, companies can improve their financial performance and create long-term value for shareholders.

Corporate Governance and Corporate Social Responsibility LU BBA 6th Semester NEP Notes

Unit 1 [Book]
Introduction to Corporate Governance VIEW
Significance, Functions of Corporate Governance VIEW
Objectives of Corporate Governance VIEW
Evolution and Development of Corporate Governance in India VIEW
Pillars and Components of Corporate Governance VIEW
Recent Development in Corporate Governance VIEW


Unit 2 [Book]
Corporate Governance Theories VIEW
Organizational Theories (including Stewardship, Resource, and Institutional Theory) VIEW
Economic Theories (such as Agency, Finance and Managerial Theory) VIEW
Stakeholder Theory VIEW
Corporate Governance and Corporate Performance guidelines in Companies VIEW
Corporate Governance Case Study VIEW


Unit 3 [Book]
Corporate Governance and Corporate Social Responsibility VIEW
Early Roots of Corporate Social Responsibility VIEW
Does Corporate Social Responsibility improve Financial Performance? VIEW
Sustainability and a Stakeholder Perspective of CSR VIEW
Criticism of Corporate Social Responsibility VIEW
Sustainability Reporting VIEW


Unit 4 [Book]
Implementing Corporate governance standards in the United States VIEW
Implementing Corporate governance standards in European Union countries VIEW
Implementing Corporate governance standards in emerging countries VIEW
International Aspects of Corporate Social Responsibility VIEW
Stakeholder engagement VIEW

Value of the Firm, Needs, Steps, Theories, Factors Affecting

The Value of the Firm refers to the total economic worth of a business based on the present value of its expected future cash flows and the claims of both debt holders and equity shareholders. It represents the value created by the company’s assets, operations, investment opportunities and financing decisions. In financial management, firm value is an important measure for evaluating the overall financial position and performance of a company. Management aims to maximise firm value by making efficient investment, financing and dividend decisions. The value of the firm is influenced by profitability, risk, growth prospects, cost of capital, cash flows and market conditions.

Needs of Determination of Value of the Firm:

1. Investment Decisions

Determining the value of the firm helps management assess whether the company’s investments are creating sufficient economic value. The value reflects the expected future cash flows generated by business assets and projects. By comparing the present value of expected benefits with investment costs, management can identify profitable investment opportunities and avoid projects that may reduce firm value. This is particularly important in capital budgeting, expansion and replacement decisions. Therefore, determining firm value provides a financial basis for selecting investments that are expected to contribute positively to the company’s long term financial performance.

2. Financing Decisions

The value of the firm is important when making financing decisions because the choice between debt and equity can influence risk and the overall cost of capital. Management can evaluate how different financing structures affect the present value of future cash flows and the claims of investors. An appropriate financing mix may help reduce the cost of capital and increase firm value. Therefore, determining firm value helps management assess whether a proposed financing decision is likely to improve financial efficiency, maintain financial stability and contribute to the long term interests of shareholders.

3. Shareholder Wealth Maximisation

Determining the value of the firm is essential for achieving the objective of shareholder wealth maximisation. Shareholders are interested in the economic value of their investment, which is influenced by the firm’s future earnings, cash flows, growth opportunities and risk. Management can use firm valuation to assess whether business decisions are increasing or decreasing shareholder wealth. Investment, financing and dividend decisions can then be evaluated according to their impact on firm value. Therefore, accurate valuation provides a useful basis for aligning managerial decisions with the objective of creating long term shareholder value.

4. Mergers and Acquisitions

Firm valuation is important in mergers, acquisitions and business combinations because both the acquiring and target companies need to determine a reasonable transaction value. The value of the target firm helps the acquiring company decide how much it should pay and whether the expected benefits justify the investment. Similarly, the target company can use valuation to assess whether the offer adequately reflects its economic worth. Therefore, determining firm value supports negotiation, pricing and decision making in mergers and acquisitions and helps reduce the risk of paying an excessive or inadequate price.

5. Business Performance Evaluation

Determining the value of the firm helps management evaluate the overall performance of the business. Changes in firm value over time may reflect changes in profitability, cash flows, growth opportunities, risk and efficiency of resource utilisation. If firm value increases, it may indicate that management decisions are generating economic benefits for investors. A decline in value may indicate problems requiring corrective action. Therefore, firm valuation provides a broader performance measure than accounting profit alone and helps management assess whether business operations are contributing to sustainable economic value creation.

6. Capital Structure Planning

Firm value is important in determining an appropriate capital structure. Different combinations of debt and equity can influence interest obligations, financial risk, tax benefits and the overall cost of capital. Management can evaluate how changes in leverage affect the value of the firm and determine whether additional borrowing is beneficial or excessive. Excessive debt may increase financial distress risk and reduce firm value, while an appropriate level of debt may provide financing advantages. Therefore, valuation helps management identify a capital structure that balances financing benefits with financial risk.

7. Dividend Policy Decisions

Determining the value of the firm helps management evaluate the effect of dividend decisions on shareholder wealth. Paying dividends provides immediate returns to shareholders, while retaining earnings provides funds for future investment and growth. The appropriate decision depends on the company’s investment opportunities, expected returns and cost of capital. Management can assess whether retaining profits is likely to increase future firm value or whether distributing them would better serve shareholders. Therefore, firm valuation provides a useful framework for balancing dividend payments with reinvestment requirements.

8. Business Sale or Restructuring

Firm valuation is necessary when a company plans to sell a business division, restructure operations or dispose of specific assets. Management needs to understand the economic value of the business or assets before deciding whether a proposed transaction is financially beneficial. Valuation helps identify whether the expected sale proceeds adequately reflect the future income generating capacity of the business. It can also support decisions regarding restructuring, asset disposal and strategic changes. Therefore, determining firm value helps management make informed decisions when changing the size or structure of the organisation.

9. Attracting Investors

Determining firm value is important for attracting potential investors because investors need information about the economic worth and future prospects of a company. A valuation based on expected cash flows, growth and risk can provide an indication of the company’s intrinsic value. Existing and potential investors can compare this value with the market price of shares when making investment decisions. A strong valuation supported by sound financial performance may improve investor confidence. Therefore, firm valuation supports investment decisions and helps communicate the financial strength and future potential of the business.

10. Strategic Decision Making

Firm valuation supports strategic decisions involving expansion, diversification, new product development and entry into new markets. Such decisions can require substantial financial resources and may significantly affect future cash flows and risk. Management can estimate how a proposed strategy may influence the overall value of the firm before committing resources. Strategies expected to increase future cash flows or reduce risk may enhance firm value, while unsuccessful strategies may reduce it. Therefore, determining firm value provides a long term financial perspective for evaluating major strategic choices and supporting sustainable business growth.

Steps of Determination of Value of the Firm:

1. Estimate Future Cash Flows

The first step in determining the value of a firm is to estimate its future cash flows. Management forecasts the cash that the business is expected to generate from its operations and investments over the relevant period. Revenue, operating expenses, taxes, working capital requirements and capital expenditure are considered while preparing these estimates. The quality of valuation depends heavily on the reliability of these forecasts. Therefore, realistic assumptions based on historical performance, industry conditions, market trends and expected business growth should be used to estimate future cash flows accurately.

2. Determine the Forecast Period

The next step is to determine the period for which future cash flows can be reasonably forecast. This period depends on the nature, stability and growth prospects of the business. During the forecast period, individual annual cash flows are estimated based on expected operating and investment activities. For mature companies, forecasts may be relatively stable, while rapidly growing businesses may require more detailed projections. Therefore, selecting an appropriate forecast period is important because unrealistic long term assumptions can significantly affect the estimated value of the firm.

3. Estimate Terminal Value

After the explicit forecast period, the firm is assumed to continue generating cash flows. The value of these future cash flows is represented by the terminal value. It is particularly important because a significant portion of the firm’s total value may arise from cash flows beyond the forecast period. The terminal value can be calculated using the perpetuity growth method or an exit multiple approach. Under the perpetuity method, sustainable growth and the appropriate discount rate are considered. Therefore, realistic assumptions are essential while estimating terminal value.

Formula:

TV = FCFₙ₊₁ / K−g ​​

Where:

TV = Terminal Value
FCFₙ₊₁ = Cash flow in the following year
K = Appropriate discount rate
g = Long term growth rate

4. Determine the Appropriate Discount Rate

The next step is to determine the appropriate discount rate for converting future cash flows into their present values. The rate should reflect the time value of money and the risk associated with the expected cash flows. For firm valuation using Free Cash Flow to Firm, the Weighted Average Cost of Capital is generally used. A higher discount rate reduces the present value of future cash flows, while a lower rate increases it. Therefore, accurate estimation of the discount rate is essential for obtaining a reliable value of the firm.

5. Calculate Present Value of Cash Flows

Once future cash flows and the appropriate discount rate have been estimated, each future cash flow is converted into its present value. This recognises that money received in the future is worth less than money available today because of the time value of money and investment risk. The present values of annual cash flows are calculated using the selected discount rate. The present value of terminal value is also calculated. Therefore, discounting future cash flows provides the foundation for determining the current economic value of the firm.

Formula:

PV = CFₜ / (1+K)t​​

Where:
PV = Present Value
CFₜ = Cash flow in year t
K = Discount rate
t = Time period

6. Calculate Enterprise Value

Enterprise value represents the value of the firm’s operating business before considering the separate claims of debt and cash. It is generally calculated by adding the present values of forecast Free Cash Flows to Firm and the present value of terminal value. This provides an estimate of the total value attributable to all providers of capital. Enterprise value is useful for comparing businesses because it focuses on operating value rather than only the market value of equity. Therefore, calculating enterprise value is an important stage in firm valuation.

Formula:

EV = PV of Forecast FCF + PV of Terminal Value

7. Adjust for Debt and Other Claims

After determining enterprise value, adjustments are made for debt and other claims that have priority over ordinary equity shareholders. Financial debt and certain other liabilities may be deducted, while excess cash and relevant non operating assets may be added, depending on the valuation framework. This adjustment converts enterprise value into the value attributable to equity shareholders. Careful identification of debt and other claims is important to avoid overstating or understating equity value. Therefore, this step establishes the portion of total business value belonging to ordinary shareholders.

Basic Formula:

Equity Value = Enterprise Value − Debt + Cash

8. Determine Equity Value per Share

The final step is to determine the value attributable to each equity share. After calculating the total equity value, it is divided by the number of outstanding equity shares. This provides an estimated intrinsic value per share. Management and investors can compare this estimated value with the current market price to assess whether the shares appear relatively undervalued or overvalued. The reliability of the result depends on the accuracy of cash flow forecasts, growth assumptions, discount rate and other valuation inputs. Thus, per share value provides a practical conclusion to the valuation process.

Formula:

Theories of Determination of Value of the Firm:

1. Net Income Approach

The Net Income Approach states that the value of a firm is influenced by its capital structure and the cost of debt and equity. According to this approach, debt is generally considered a cheaper source of finance than equity because interest cost is relatively lower. Therefore, increasing the proportion of debt can reduce the overall cost of capital and increase the total value of the firm, assuming other conditions remain unchanged. The approach suggests that an optimum capital structure can be achieved by using more debt. However, it assumes that the cost of debt and cost of equity remain constant.

Formula:

V = E + D

Where,

V = Value of Firm

E = Value of Equity

D = Value of Debt.

2. Net Operating Income Approach

The Net Operating Income Approach argues that the total value of the firm is independent of its capital structure. According to this theory, changes in the proportion of debt and equity do not affect the overall value of the firm because any benefit from cheaper debt is offset by an increase in the cost of equity. As financial leverage increases, equity shareholders perceive greater financial risk and demand higher returns. Consequently, the overall cost of capital remains constant. Therefore, under this approach, firm value is determined mainly by operating income and the overall capitalisation rate.

Formula:

V = NOI / Ko​

Where

V = Value of Firm

NOI = Net Operating Income

Kₒ = Overall Cost of Capital.

3. Traditional Approach

The Traditional Approach takes a balanced view between the Net Income and Net Operating Income approaches. It suggests that capital structure can influence the value of the firm up to a certain point. Initially, increasing debt may reduce the overall cost of capital because debt is relatively cheaper than equity. After reaching an optimum level of debt, further borrowing increases financial risk and raises the cost of equity and debt. Consequently, the overall cost of capital begins to increase and firm value decreases. Therefore, this approach supports the existence of an optimal capital structure.

Basic Relationship:

V = EBIT(1−T) / Ko

The optimum structure occurs where

Kₒ is minimum and firm value is maximum.

4. Modigliani and Miller Theory

The Modigliani and Miller Theory states that, under certain ideal market assumptions, the value of a firm is independent of its capital structure. Investors can make their own financing adjustments, so changing the debt and equity mix does not create additional firm value. In the original proposition without taxes, the overall cost of capital remains constant. When corporate taxes are introduced, debt can increase firm value because interest provides a tax advantage. The theory provides an important framework for understanding the relationship between capital structure, financing decisions and firm value.

Without Tax:

Vₗ = Vᵤ

Where Vₗ = Levered Firm Value and Vᵤ = Unlevered Firm Value.

With Corporate Tax:

Vₗ = Vᵤ + (T x D)

Where

T = Corporate Tax Rate

D = Debt.

5. Dividend Capitalisation Approach

The Dividend Capitalisation Approach determines the value of equity based on the present value of expected future dividends. It assumes that investors value shares according to the income they expect to receive from them. Expected dividends, required rate of return and dividend growth are therefore important factors in determining share value. A higher expected dividend or growth rate can increase the estimated value, while a higher required return generally reduces it. This approach is particularly useful for companies with stable dividend policies and predictable dividend growth.

Formula:

P₀ = D1 / Kₑ − g​​

Where,

P₀ = Current Share Value,

D₁ = Expected Dividend,

Kₑ = Cost of Equity and

g = Growth Rate.

6. Free Cash Flow Approach

The Free Cash Flow Approach determines the value of a firm based on the present value of its expected future free cash flows. It focuses on the cash generated by business operations after meeting necessary operating expenses and investment requirements. These future cash flows are discounted using an appropriate rate, commonly WACC for Free Cash Flow to Firm. The approach is widely used because cash flow reflects the economic benefits generated by the business. Therefore, firm value depends on expected future cash generation, growth prospects, investment requirements and the risk associated with those cash flows.

Formula:
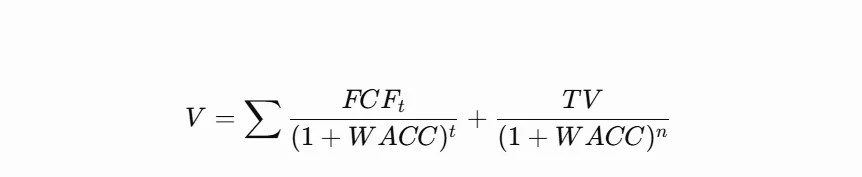
Where,

FCF = Free Cash Flow

WACC = Weighted Average Cost of Capital

TV = Terminal Value.

Factors Affecting the Value of the Firm:

1. Profitability and Earnings Potential

The value of a firm is fundamentally driven by its profitability and capacity to generate sustainable earnings over time, as higher and more consistent profits translate into greater cash flows available for shareholders and reinvestment. Firms demonstrating strong operating margins, efficient cost management, and consistent revenue growth are typically valued higher by investors and markets. Profitability reflects the firm’s competitive positioning, operational efficiency, and ability to convert business activities into tangible financial returns. Since most valuation models, including discounted cash flow and earnings multiples, are anchored in earnings or cash flow projections, a firm’s demonstrated and expected profitability remains one of the most significant determinants of overall firm value.

2. Capital Structure and Cost of Capital

The mix of debt and equity financing a firm employs significantly influences its overall value through its impact on the weighted average cost of capital. An optimal capital structure minimizes the overall cost of financing, thereby maximizing firm value, while excessive debt increases financial risk and potential distress costs, and excessive reliance on equity may dilute returns and increase the cost of capital. Firms that strategically balance leverage to exploit tax benefits of debt while managing associated risks tend to achieve a lower cost of capital, which directly enhances the present value of future cash flows and, consequently, overall firm valuation.

3. Growth Prospects and Future Opportunities

A firm’s anticipated future growth, including expansion into new markets, product innovation, and increasing market share, plays a critical role in determining its value, as investors price in expected future cash flows rather than solely historical performance. Firms with strong growth prospects, supported by sustainable competitive advantages, innovative capabilities, or favorable industry positioning, typically command higher valuations due to the expectation of increasing future earnings and cash flows. Growth potential is often reflected in valuation multiples and terminal value calculations within discounted cash flow models, making a firm’s credible and achievable growth trajectory a key driver of overall enterprise value.

4. Dividend Policy

A firm’s dividend policy, reflecting decisions on the proportion of earnings distributed to shareholders versus retained for reinvestment, influences firm value by signaling financial health and shaping investor expectations regarding future returns. Consistent and sustainable dividend payments can enhance investor confidence and attract income-focused investors, potentially supporting share price stability. Conversely, firms retaining earnings for high-return growth opportunities may achieve greater long-term value creation if reinvested capital generates returns exceeding shareholders’ required rate of return. The appropriateness of a firm’s dividend policy, aligned with its growth stage and investment opportunities, therefore directly impacts market perception and overall valuation.

5. Business and Financial Risk Profile

The overall risk profile of a firm, encompassing both business risk arising from operational and industry factors, and financial risk stemming from leverage and capital structure choices, significantly affects its value through the discount rate applied to future cash flows. Higher perceived risk increases the required rate of return demanded by investors, thereby reducing the present value of expected future cash flows and lowering overall firm valuation. Firms that effectively manage and mitigate operational uncertainties, market volatility, and financial leverage tend to enjoy lower risk premiums, resulting in higher valuations compared to firms with similar earnings but greater underlying risk exposure.

6. Quality of Management and Corporate Governance

The competence, strategic vision, and integrity of a firm’s management team, along with robust corporate governance practices, significantly influence firm value by affecting operational efficiency, strategic decision-making, and stakeholder confidence. Strong management teams capable of effectively allocating capital, navigating competitive challenges, and executing growth strategies tend to enhance long-term value creation. Additionally, transparent governance structures, effective board oversight, and alignment of management interests with shareholders reduce agency costs and investor uncertainty. Markets often assign valuation premiums to firms perceived as having capable leadership and sound governance, while poor management or governance failures can lead to significant value destruction.

Theories of Corporate Governance

Corporate Governance theories encompass various perspectives and frameworks that guide the structure, processes, and relationships within corporations to ensure accountability, transparency, and fairness. These theories have evolved over time in response to changes in business environments, regulatory frameworks, and societal expectations.

  • Agency Theory

Developed in the 1970s, agency theory addresses the principal-agent problem, which arises when the interests of shareholders (principals) diverge from those of managers (agents). According to this theory, managers may act in their own interests rather than maximizing shareholder value. Mechanisms such as executive compensation, board oversight, and disclosure requirements are employed to align the interests of managers with those of shareholders.

  • Stewardship Theory

In contrast to agency theory, stewardship theory suggests that managers are inherently trustworthy and will act in the best interests of shareholders. It emphasizes the importance of building trust between managers and shareholders, as well as fostering a sense of stewardship and responsibility among managers. Stewardship theory advocates for less monitoring and control mechanisms, relying instead on shared values and long-term relationships.

  • Stakeholder Theory:

Stakeholder theory expands the focus of corporate governance beyond shareholders to include all stakeholders who are affected by or can affect the corporation, such as employees, customers, suppliers, communities, and the environment. It argues that corporations should consider the interests of all stakeholders and seek to create value for them, not just shareholders. Stakeholder theory emphasizes corporate social responsibility (CSR) and sustainable business practices.

  • Resource Dependence Theory:

Resource dependence theory examines how corporations interact with their external environment to acquire the resources they need for survival and growth. It suggests that corporations are dependent on various stakeholders for resources such as capital, labor, technology, and information. Effective corporate governance involves managing these dependencies through strategic relationships, alliances, and diversification strategies.

  • Transaction Cost Economics:

Transaction cost economics (TCE) focuses on the costs associated with conducting economic transactions within organizations. It suggests that firms exist to minimize transaction costs, which include the costs of negotiating, monitoring, and enforcing contracts. Corporate governance mechanisms such as vertical integration, outsourcing, and the choice of organizational structure are influenced by TCE principles to mitigate transaction costs.

  • Institutional Theory:

Institutional theory examines how corporations are influenced by social, cultural, and institutional contexts. It suggests that corporate governance practices are shaped not only by economic factors but also by institutional norms, regulations, and societal expectations. Institutional theorists argue that corporations conform to prevailing institutional norms to gain legitimacy and support from stakeholders.

  • Ethical Leadership Theory:

Ethical leadership theory emphasizes the role of leaders in shaping the ethical culture of organizations. It suggests that ethical leaders who demonstrate integrity, transparency, and accountability set the tone for ethical behavior throughout the organization. Corporate governance mechanisms such as codes of conduct, ethics training, and whistleblower protection aim to promote ethical leadership and decision-making.

  • Dynamic Capabilities Theory:

Dynamic capabilities theory focuses on a firm’s ability to adapt and innovate in response to changing market conditions and competitive pressures. It suggests that corporate governance should facilitate the development of dynamic capabilities by fostering a culture of learning, experimentation, and risk-taking. Flexibility, agility, and responsiveness are key principles of dynamic capabilities theory.

  • Legitimacy Theory:

Legitimacy theory argues that corporations must maintain legitimacy in the eyes of society to secure their continued existence and success. It suggests that corporate governance practices are influenced by the need to gain and maintain legitimacy through compliance with legal, ethical, and social norms. Transparency, accountability, and corporate social responsibility are central to legitimacy theory.

  • Network Theory:

Network theory explores the relationships and interdependencies among actors within corporate networks, such as boards of directors, executive teams, investors, and other stakeholders. It suggests that corporate governance effectiveness depends on the strength and quality of these networks, as well as the flow of information and resources among network members. Network theory emphasizes the importance of social capital and relational governance mechanisms.

Objective and Need of Corporate Governance

Corporate Governance encompasses the systems, processes, and practices by which companies are directed and controlled. It aims to safeguard shareholders’ interests, enhance transparency and accountability, manage risks, foster ethical conduct, improve decision-making, and promote long-term sustainability, thereby ensuring the company’s success and stakeholders’ trust.

Objective of Corporate Governance:

  • Enhancing Transparency:

Corporate governance aims to ensure that all stakeholders have access to accurate, relevant, and timely information about the company’s performance, financial condition, and decision-making processes.

  • Promoting Accountability:

It seeks to establish clear lines of responsibility and accountability throughout the organization, ensuring that decision-makers are held responsible for their actions and outcomes.

  • Safeguarding Shareholder Interests:

Corporate governance aims to protect the rights and interests of shareholders by ensuring fair treatment, equitable access to information, and mechanisms for recourse in case of misconduct or negligence.

  • Managing Risk:

It involves implementing effective risk management processes to identify, assess, and mitigate risks that may impact the company’s operations, finances, reputation, and stakeholders.

  • Fostering Ethical Conduct:

Corporate governance promotes a culture of integrity, honesty, and ethical behavior within the organization, setting standards for acceptable conduct and enforcing compliance with laws, regulations, and ethical principles.

  • Improving Decision-making:

By establishing clear structures, processes, and mechanisms for decision-making, corporate governance aims to facilitate informed and strategic decision-making that aligns with the company’s objectives and creates long-term value.

  • Enhancing Long-term Sustainability:

Corporate governance focuses on ensuring the company’s long-term sustainability and resilience by balancing short-term interests with the needs of future generations, considering environmental, social, and governance (ESG) factors, and fostering responsible business practices.

Need of Corporate Governance:

  • Protection of Shareholder Interests:

Corporate governance ensures that the rights and interests of shareholders, who have invested their capital in the company, are protected. This includes mechanisms for fair treatment, equitable access to information, and safeguards against abuse of power by management.

  • Enhanced Transparency and Accountability:

Good corporate governance promotes transparency by providing stakeholders with accurate, timely, and relevant information about the company’s performance, financial health, and decision-making processes. It also fosters accountability by establishing clear lines of responsibility and consequences for actions.

  • Effective Risk Management:

Corporate governance frameworks help identify, assess, and mitigate risks that may affect the company’s operations, finances, reputation, and stakeholders. By implementing robust risk management practices, companies can enhance their resilience and ability to navigate challenges.

  • Ethical Conduct and Compliance:

Ethical behavior is fundamental to corporate governance, as it ensures that the company operates with integrity, honesty, and respect for laws, regulations, and ethical standards. By fostering a culture of ethics and compliance, corporate governance helps prevent misconduct and promotes trust among stakeholders.

  • Improved Decision-making Processes:

Clear governance structures and processes facilitate informed and strategic decision-making within the organization. By defining roles, responsibilities, and decision-making authorities, corporate governance enables efficient and effective decision-making that aligns with the company’s objectives and values.

  • Long-term Sustainability and Value Creation:

Corporate governance emphasizes the long-term sustainability and value creation of the company. By considering environmental, social, and governance (ESG) factors, companies can mitigate risks, identify opportunities, and create value for all stakeholders over the long term.

  • Stakeholder Engagement and Trust:

Good corporate governance fosters constructive engagement with stakeholders, including employees, customers, suppliers, and communities. By listening to stakeholders’ concerns, addressing their interests, and building trust through transparent and accountable actions, companies can enhance their reputation and resilience.

Organization Theory

The Organizational Theory refers to the set of interrelated concepts, definitions that explain the behavior of individuals or groups or subgroups, who interacts with each other to perform the activities intended towards the accomplishment of a common goal.

In other words, the organizational theory studies the effect of social relationships between the individuals within the organization along with their actions on the organization as a whole. Also, it studies the effects of internal and external business environment such as political, legal, cultural, etc. on the organization.

The term organization refers to the group of individuals who come together to perform a set of tasks with the intent to accomplish the common objectives. The organization is based on the concept of synergy, which means, a group can do more work than an individual working alone.

Thus, in order to study the relationships between the individuals working together and their overall effect on the performance of the organization is well explained through the organizational theories. Some important organizational theories are:

  1. Classical Theory
  2. Scientific Management Theory
  3. Administrative Theory
  4. Bureaucratic Theory
  5. Neo-Classical Theory
  6. Modern Theory

An organizational structure plays a vital role in the success of any enterprise. Thus, the organizational theories help in identifying the suitable structure for an organization, efficient enough to deal with the specific problems.

Classical Theory

The Classical Theory is the traditional theory, wherein more emphasis is on the organization rather than the employees working therein. According to the classical theory, the organization is considered as a machine and the human beings as different components/parts of that machine.

The classical theory has the following characteristics:

  1. It is built on an accounting model.
  2. It lays emphasis on detecting errors and correcting them once they have been committed.
  3. It is more concerned with the amount of output than the human beings.
  4. The human beings are considered to be relatively homogeneous and unmodifiable. Thus, labor is not divided on the basis of different kinds of jobs to be performed in an organization.
  5. It is assumed that employees are relatively stable in terms of the change, in an organization.
  6. It is assumed that the authority and control should be vested with the central authority only, in order to have a centralized and integrated system.

Some writers of the classical theory emphasized on the technological aspects of the organization and how the individuals can be made more efficient, while others emphasized on the structural aspects of an organization so that individuals collectively can be made more efficient. Thus, this purview of different writers resulted in the formation of two distinct streams:

  • Scientific Management Stream
  • Administrative Management Stream

Thus, according to this theory the human beings are just considered as a means of production.

Scientific Management Theory

Scientific Management Theory is well known for its application of engineering science at the production floor or the operating levels. The major contributor of this theory is Fredrick Winslow Taylor, and that’s why the scientific management is often called as “Taylorism”.

The scientific management theory focused on improving the efficiency of each individual in the organization. The major emphasis is on increasing the production through the use of intensive technology, and the human beings are just considered as adjuncts to machines in the performance of routine tasks.

The scientific management theory basically encompasses the work performed on the production floor as these tasks are quite different from the other tasks performed within the organization. Such as, these are repetitive in nature, and the individual workers performing their daily activities are divided into a large number of cyclical repetition of same or closely related activities. Also, these activities do not require the individual worker to exercise complex-problem solving activity. Therefore, more attention is required to be imposed on the standardization of working methods and hence the scientific management theory laid emphasis on this aspect.

The major principles of scientific management, given by Taylor, can be summarized as follows:

  • Separate planning from doing.
  • The Functional foremanship of supervision,i.e. Eight supervisors required to give directions and instructions in their respective fields.
  • Time, motion and fatigue studies shall be used to determine the fair amount of work done by each individual worker.
  • Improving the working conditions and standardizing the tools, period of work and cost of production.
  • Proper scientific selection and training of workmen should be done.
  • The financial incentives should be given to the workers to boost their productivity and motivate them to perform well.

Thus, the scientific management theory focused more on mechanization and automation, i.e., technical aspects of efficiency rather than the broader aspects of human behavior in the organization.

Administrative Theory

Administrative Theory is based on the concept of departmentalization, which means the different activities to be performed for achieving the common purpose of the organization should be identified and be classified into different groups or departments, such that the task can be accomplished effectively.

The administrative theory is given by Henri Fayol, who believed that more emphasis should be laid on organizational management and the human and behavioral factors in the management. Thus, unlike the scientific management theory of Taylor where more emphasis was on improving the worker’s efficiency and minimizing the task time, here the main focus is on how the management of the organization is structured and how well the individuals therein are organized to accomplish the tasks given to them.

The other difference between these two is, the administrative theory focuses on improving the efficiency of management first so that the processes can be standardized and then moves to the operational level where the individual workers are made to learn the changes and implement those in their routine jobs. While in the case of the scientific management theory, it emphasizes on improving the efficiency of the workers at the operating level first which in turn improves the efficiency of the management. Thus, the administrative theory follows the top-down approach while the scientific management theory follows the bottom-up approach.

Bureaucratic Theory

Bureaucratic Theory is related to the structure and administrative process of the organization and is given by Max Weber, who is regarded as the father of bureaucracy. What is Bureaucracy? The term bureaucracy means the rules and regulations, processes, procedures, patterns, etc. that are formulated to reduce the complexity of organization’s functioning.

According to Max Weber, the bureaucratic organization is the most rational means to exercise a vital control over the individual workers. A bureaucratic organization is one that has a hierarchy of authority, specialized work force, standardized principles, rules and regulations, trained administrative personnel, etc.

The Weber’s bureaucratic theory differs from the traditional managerial organization in the sense; it is impersonal, and the performance of an individual is judged through rule-based activity and the promotions are decided on the basis of one’s merits and performance.

Also, there is a hierarchy in the organization, which represents the clear lines of authority that enable an individual to know his immediate supervisor to whom he is directly accountable. This shows that bureaucracy has many implications in varied fields of organization theory.

Thus, Weber’s bureaucratic theory contributes significantly to the classical organizational theory which explains that precise organization structure along with the definite lines of authority is required in an organization to have an effective workplace.

Modern Theory

Modern Theory is the integration of valuable concepts of the classical models with the social and behavioral sciences. This theory posits that an organization is a system that changes with the change in its environment, both internal and external.

There are several features of the modern theory that make it distinct from other sets of organizational theories, these are:

  1. The modern theory considers the organization as an open system. This means an organization consistently interacts with its environment, so as to sustain and grow in the market. Since, the organization adopts the open system several elements such as input, transformation, process, output, feedback and environment exists. Thus, this theory differs from the classical theory where the organization is considered as a closed system.
  2. Since the organization is treated as an open system, whose survival and growth is determined by the changes in the environment, the organization is said to be adaptive in nature, which adjusts itself to the changing environment.
  3. The modern theory considers the organization as a system which is dynamic.
  4. The modern theory is probabilistic and not deterministic in nature. A deterministic model is one whose results are predetermined and whereas the results of the probabilistic models are uncertain and depends on the chance of occurrence.
  5. This theory encompasses multilevel and multidimensional aspects of the organization. This means it covers both the micro and macro environment of the organization. The macro environment is external to the organization, while the micro environment is internal to the organization.
  6. The modern theory is multi-variable, which means it considers multiple variables simultaneously. This shows that cause and effect are not simple phenomena. Instead, the event can be caused as a result of several variables which could either be interrelated or interdependent.

The scientists from different fields have made major contributions to the modern theory. They emphasized on the importance of communication and integration of individual and organizational interest as prerequisites for the smooth functioning of the organization.

Neo-Classical theory

The Neo-Classical Theory is the extended version of the classical theory wherein the behavioral sciences gets included into the management. According to this theory, the organization is the social system, and its performance does get affected by the human actions.

The classical theory laid emphasis on the physiological and mechanical variables and considered these as the prime factors in determining the efficiency of the organization. But, when the efficiency of the organization was actually checked, it was found out that, despite the positive aspect of these variables the positive response in work behavior was not evoked.

Thus, the researchers tried to identify the reasons for human behavior at work. This led to the formation of a NeoClassical theory which primarily focused on the human beings in the organization. This approach is often referred to as “behavioral theory of organization” or “human relations” approach in organizations.

The NeoClassical theory posits that an organization is the combination of both the formal and informal forms of organization, which is ignored by the classical organizational theory. The informal structure of the organization formed due to the social interactions between the workers affects and gets affected by the formal structure of the organization. Usually, the conflicts between the organizational and individual interest exist, thus the need to integrate these arises.

The NeoClassical theory asserts that an individual is diversely motivated and wants to fulfill certain needs. The communication is an important yardstick to measure the efficiency of the information being transmitted from and to different levels of the organization. The teamwork is the prerequisite for the sound functioning of the organization, and this can be achieved only through a behavioral approach, i.e. how individual interact and respond to each other.

error: Content is protected !!