Strategic Decision Making

Strategic decision-making is the process of charting a course based on long-term goals and a longer term vision. By clarifying your company’s big picture aims, you’ll have the opportunity to align your shorter term plans with this deeper, broader mission giving your operations clarity and consistency.

Strategic decision making involves the following 3 things:

  • The long term way forward for the company
  • Selection of proper markets for the company
  • The products and tactics needed to succeed in the targeted market.

Features of Strategic Decision Making

  1. Strategy is at many times at tangent with Marketing Decisions

Where marketing decisions are short term, strategic decision making might consider a long term initiative, such as launching a very new and innovative product, or changing the existing product lines radically. Technology or innovation is at the crux of strategic decision making.

The reason that marketing decisions and strategy decisions are difference is because marketing is focused on retaining the existing customer base with the existing technologies. But the customer base is sure to get tired soon of the existing products and the innovators and adopters will keep searching for new products in the market. And hence, through strategic decisions, the firm has to stay in a place of continuous development.

  1. There is immense risk involved while taking strategic decisions

Naturally, when you are implementing plans which will show positive or negative results only after 4-5 years, the risk in strategic decision making is huge. Think about the time and energy, not to say natural resources wasted to implement a plan which failed after 4-5 years.

Yet, even after the risk involved, companies have to implement risky strategic decisions from time to time just because the directors thought a unique product had demand in the market, or that another product is required in the market. Strategic decisions involve necessary risk and success is not guaranteed.

  1. Strategic decisions involve a lot of Ifs and Buts

Think of a mind map and the number of branches and nodes that can form the complete mind map. When a brain starts thinking, the central thought might have further branches, and these branches will have even more nodes (or sub branches if you want to call them)

Similar to the mind map, a business can face many problems in the course of its run. A competitor can crop up, the market can become penetrative, the external environment can change, and many other unforeseen situations can happen. The strategic decision making has to consider all these alternatives, whether positive or negative. And the plan has to also include the action that the firm will take, if any of the above business problems or factors come into play.

  1. Strategy implementation timelines

Whenever we make a schedule in our personal lives, we always start things when we have enough time in our hand. For example you will plan a holiday, when office work is not hectic. You will not plan it when there is a product launch nearby. Similarly, when in business, timelines are very important.

If a product is to be launched, the launch date is decided at least a year back, the sales phase has to be implemented at least 2 months before the actual launch so that you have sellers in place when the product is launch. Moreover, the service network is also to be planned before the launch, so that service issues are sorted out when there are problems after the product launch. If these concepts are not implemented, the marketing strategy and hence the product can fail miserably.

  1. Preparing for the competition’s response

Whenever you change the market equilibrium, the competitors, whose businesses you have directly challenged, are sure to respond. When they respond, the market changes and you have to change your strategy accordingly.

In general there are 2 ways that a company directly affects the competition and the market.

  • The company creates a completely new operating norm in the market itself.
  • It raises customer expectations and thereby changes the market equilibrium.

Most strategic decisions will call for radical changes in the way the company operates in the existing market. Accordingly, the perception of competitors and customers will change for the company. The company has to in turn be prepared for the response of competitors in such a case.

Implementation of strategic decisions While implementing strategic decisions, you need to have eyes at the front as well as the back of your head. You need to look at what was decided at the start, as due to short term pressure, it is very much possible to deviate from the path which was already set.

Dealing with Risk and Uncertainty in Decision Making

Decision-making under Certainty

A condition of certainty exists when the decision-maker knows with reasonable certainty what the alternatives are, what conditions are associated with each alternative, and the outcome of each alternative. Under conditions of certainty, accurate, measurable, and reliable information on which to base decisions is available.

The cause and effect relationships are known and the future is highly predictable under conditions of certainty. Such conditions exist in case of routine and repetitive decisions concerning the day-to-day operations of the business.

Decision-making under Risk

When a manager lacks perfect information or whenever an information asymmetry exists, risk arises. Under a state of risk, the decision maker has incomplete information about available alternatives but has a good idea of the probability of outcomes for each alternative.

While making decisions under a state of risk, managers must determine the probability associated with each alternative on the basis of the available information and his experience.

Decision-making under Uncertainty

Most significant decisions made in today’s complex environment are formulated under a state of uncertainty. Conditions of uncertainty exist when the future environment is unpredictable and everything is in a state of flux. The decision-maker is not aware of all available alternatives, the risks associated with each, and the consequences of each alternative or their probabilities.

The manager does not possess complete information about the alternatives and whatever information is available, may not be completely reliable. In the face of such uncertainty, managers need to make certain assumptions about the situation in order to provide a reasonable framework for decision-making. They have to depend upon their judgment and experience for making decisions.

Modern Approaches to Decision-making under Uncertainty

There are several modern techniques to improve the quality of decision-making under conditions of uncertainty.

The most important among these are:

  • Risk analysis
  • Decision trees
  • Preference theory

Risk Analysis

Managers who follow this approach analyze the size and nature of the risk involved in choosing a particular course of action.

For instance, while launching a new product, a manager has to carefully analyze each of the following variables the cost of launching the product, its production cost, the capital investment required, the price that can be set for the product, the potential market size and what percent of the total market it will represent.

Risk analysis involves quantitative and qualitative risk assessment, risk management and risk communication and provides managers with a better understanding of the risk and the benefits associated with a proposed course of action. The decision represents a trade-off between the risks and the benefits associated with a particular course of action under conditions of uncertainty.

Decision Trees

These are considered to be one of the best ways to analyze a decision. A decision-tree approach involves a graphic representation of alternative courses of action and the possible outcomes and risks associated with each action.

By means of a “tree” diagram depicting the decision points, chance events and probabilities involved in various courses of action, this technique of decision-making allows the decision-maker to trace the optimum path or course of action.

Preference or Utility Theory

This is another approach to decision-making under conditions of uncertainty. This approach is based on the notion that individual attitudes towards risk vary. Some individuals are willing to take only smaller risks (“risk averters”), while others are willing to take greater risks (“gamblers”). Statistical probabilities associated with the various courses of action are based on the assumption that decision-makers will follow them.

3For instance, if there were a 60 percent chance of a decision being right, it might seem reasonable that a person would take the risk. This may not be necessarily true as the individual might not wish to take the risk, since the chances of the decision being wrong are 40 percent. The attitudes towards risk vary with events, with people and positions.

Top-level managers usually take the largest amount of risk. However, the same managers who make a decision that risks millions of rupees of the company in a given program with a 75 percent chance of success are not likely to do the same with their own money.

Moreover, a manager willing to take a 75 percent risk in one situation may not be willing to do so in another. Similarly, a top executive might launch an advertising campaign having a 70 percent chance of success but might decide against investing in plant and machinery unless it involves a higher probability of success.

Though personal attitudes towards risk vary, two things are certain.

Firstly, attitudes towards risk vary with situations, i.e. some people are risk averters in some situations and gamblers in others.

Secondly, some people have a high aversion to risk, while others have a low aversion.

Most managers prefer to be risk averters to a certain extent, and may thus also forego opportunities. When the stakes are high, most managers tend to be risk averters; when the stakes are small, they tend to be gamblers.

Manpower Planning, Process, Reason, Challenges

Manpower Planning, also known as human resource planning, is the process of forecasting an organization’s future human resource needs and ensuring that the right number of qualified individuals are available to meet those needs. It involves analyzing current workforce capabilities, predicting future staffing requirements based on organizational goals and strategies, and developing plans to recruit, train, and retain employees. Effective manpower planning helps organizations optimize their human resources, minimize costs, improve productivity, and ensure that they can adapt to changing business conditions while achieving strategic objectives.

Process of Manpower Planning:

Process of manpower planning involves several steps that help organizations ensure they have the right number of employees with the necessary skills to meet their goals.

  1. Assess Organizational Objectives

  • Understand the organization’s short-term and long-term goals.
  • Align manpower planning with strategic objectives to ensure that the workforce supports business needs.
  1. Analyze Current Workforce

  • Conduct a thorough evaluation of the existing workforce to determine the number of employees, their skills, experience, and qualifications.
  • Identify strengths, weaknesses, and gaps in the current workforce.
  1. Forecast Future Manpower Needs

  • Project future staffing requirements based on factors such as business growth, upcoming projects, market trends, and technological changes.
  • Use quantitative methods (statistical analysis) and qualitative methods (expert opinions) for forecasting.
  1. Identify Gaps in Workforce

  • Compare the current workforce against the projected needs to identify gaps.
  • Determine the quantity and type of personnel required to meet future demands.
  1. Develop Recruitment Plans

  • Create strategies for recruiting new employees to fill identified gaps.
  • Consider various recruitment sources such as job postings, employee referrals, recruitment agencies, and online platforms.
  1. Implement Training and Development Programs

  • Identify skills development needs and create training programs to enhance the existing workforce’s capabilities.
  • Ensure employees are equipped with the skills required for future roles.
  1. Evaluate and Adjust Staffing Levels

  • Monitor the implementation of the staffing plan and assess its effectiveness.
  • Adjust the workforce levels and recruitment plans based on changing business conditions and feedback from management.
  1. Review and Revise Manpower Plan

  • Continuously evaluate the manpower planning process to ensure it remains aligned with the organization’s objectives and responds to internal and external changes.
  • Revise the manpower plan as needed to adapt to new business challenges or opportunities.

Reason of Manpower Planning:

  • Optimal Utilization of Resources:

Manpower planning ensures that an organization effectively utilizes its human resources, preventing both understaffing and overstaffing, which can lead to inefficiencies and increased costs.

  • Future Workforce Needs:

It helps organizations anticipate future staffing requirements based on business growth, projects, and changes in the industry, ensuring they have the right talent available when needed.

  • Skill Development and Training:

Through manpower planning, organizations can identify skill gaps within their workforce and implement training programs to develop the necessary competencies, enhancing overall productivity.

  • Employee Retention:

Effective manpower planning contributes to higher employee satisfaction by aligning individual career goals with organizational objectives, leading to improved retention rates.

  • Cost Management:

By accurately forecasting staffing needs, organizations can manage labor costs more effectively, reducing unnecessary expenses related to recruitment and training.

  • Adaptability to Change:

In a dynamic business environment, manpower planning enables organizations to quickly adapt to changes in market demand or operational needs by ensuring a flexible and capable workforce.

  • Strategic Decision-Making:

It provides essential data and insights for strategic decision-making, allowing management to align workforce capabilities with business goals and objectives.

  • Succession Planning:

Manpower planning facilitates the identification of potential leaders within the organization, ensuring a smooth transition in key positions and maintaining business continuity.

Challenges of Manpower Planning:

  1. Dynamic Business Environment

The rapid changes in the business landscape, including technological advancements, market fluctuations, and evolving consumer preferences, make it difficult to predict future manpower needs accurately. Organizations must remain agile and adaptable to respond to these changes effectively.

  1. Skill Shortages

Many industries face a shortage of skilled labor, making it challenging to find qualified candidates to fill key positions. As job requirements become more specialized, organizations may struggle to identify individuals with the necessary skills and experience, leading to potential gaps in the workforce.

  1. Inaccurate Forecasting

Forecasting future manpower needs relies on various assumptions and data analysis, which may not always be accurate. Poor forecasting can lead to overstaffing or understaffing, both of which can have negative consequences for organizational performance and employee morale.

  1. Employee Turnover

High employee turnover can disrupt manpower planning efforts. Frequent departures can create instability within teams and require ongoing recruitment and training efforts, complicating the planning process. Organizations need strategies to retain talent and minimize turnover to ensure a stable workforce.

  1. Resistance to Change

Employees may resist changes associated with manpower planning, such as new roles, restructuring, or shifts in organizational culture. Overcoming this resistance requires effective communication and change management strategies to foster acceptance and cooperation among staff.

  1. Integration with Other HR Functions

Manpower planning must be integrated with other human resource functions, such as recruitment, training, and performance management. Lack of coordination can lead to inefficiencies, misalignment, and missed opportunities for optimizing workforce capabilities.

  1. Compliance and Regulations

Organizations must navigate various labor laws and regulations that impact manpower planning, such as equal employment opportunity laws, health and safety regulations, and union agreements. Compliance with these regulations adds complexity to the planning process and can limit flexibility.

  1. Technological Integration

The integration of technology into manpower planning processes can be both a challenge and an opportunity. While technology can enhance data analysis and forecasting capabilities, organizations may face challenges in adopting new systems, training staff, and ensuring data accuracy and security.

Business Process Re-engineering, Objectives, Steps, Benefits

Business Process Re-engineering (BPR) fundamentally transforms an organization’s processes to achieve significant improvements in critical performance metrics. BPR involves rethinking and redesigning workflows and business processes from the ground up, aiming to enhance efficiency, reduce costs, and improve quality. By focusing on outcomes rather than tasks, BPR often leads to radical changes in how work is done, potentially resulting in up to a 30-50% improvement in process performance. Successful BPR initiatives require strong leadership, a clear vision, and employee engagement to overcome resistance and ensure alignment with organizational goals.

Objectives of Business Process Re-engineering:

  • Improving Efficiency

One of the primary objectives of BPR is to enhance operational efficiency. By analyzing and redesigning workflows, organizations can eliminate redundancies and streamline processes. This leads to faster turnaround times, reduced resource consumption, and ultimately, lower operational costs.

  • Enhancing Quality

BPR aims to improve the quality of products and services by identifying and addressing flaws in existing processes. By focusing on quality improvement, organizations can increase customer satisfaction and loyalty, which are critical for long-term success. This might involve implementing standardized procedures and using technology for better accuracy.

  • Increasing Flexibility

In today’s rapidly changing business environment, organizations must be agile. BPR encourages the creation of flexible processes that can quickly adapt to new market conditions, customer needs, or technological advancements. This flexibility allows companies to respond promptly to opportunities and challenges, maintaining a competitive edge.

  • Boosting Customer Satisfaction

BPR is to enhance customer experience. By re-engineering processes to be more customer-centric, organizations can provide better service, reduce response times, and meet customer needs more effectively. Increased customer satisfaction not only fosters loyalty but also attracts new clients through positive word-of-mouth.

  • Leveraging Technology

BPR emphasizes the integration of modern technologies to automate and optimize processes. By adopting new technologies, organizations can improve communication, data management, and workflow efficiency. This can result in significant cost savings and productivity gains, allowing employees to focus on higher-value tasks.

  • Fostering Innovation

BPR encourages a culture of innovation within the organization. By rethinking established processes, organizations can identify new opportunities for improvement and growth. This objective supports the development of creative solutions and innovative products, helping companies stay ahead of competitors.

  • Aligning with Strategic Goals

BPR seeks to align business processes with the overall strategic goals of the organization. By ensuring that processes support the broader objectives, companies can achieve greater coherence and synergy in their operations. This alignment facilitates better decision-making and resource allocation, ultimately driving organizational success.

Steps of Business Process Re-engineering:

  • Identify Processes for Re-engineering

Start by identifying which processes need re-engineering. This involves analyzing current workflows to pinpoint inefficiencies, bottlenecks, or areas that do not align with organizational goals. Prioritize processes that will have the most significant impact on performance and customer satisfaction.

  • Define Objectives and Goals

Clearly articulate the objectives of the re-engineering effort. Establish specific, measurable, achievable, relevant, and time-bound (SMART) goals that align with the organization’s strategic vision. These goals will guide the re-engineering process and help measure success.

  • Assemble a Cross-Functional Team

Form a team that includes members from various departments affected by the process. A cross-functional team brings diverse perspectives and expertise, which is crucial for understanding the complexities of the existing processes and for designing effective solutions.

  • Analyze Current Processes

Conduct a thorough analysis of the existing processes to understand how they function. Use tools like process mapping, flowcharts, or value stream mapping to visualize workflows. Identify inefficiencies, redundancies, and areas for improvement by examining how work is currently performed.

  • Design New Processes

Based on the analysis, design new, streamlined processes that eliminate inefficiencies and enhance performance. Focus on creating processes that are customer-centric, leveraging technology and best practices. Ensure the new design aligns with the established objectives and goals.

  • Implement Changes

Develop a detailed implementation plan that outlines the steps, timelines, and resources needed to execute the new processes. Communicate the changes to all stakeholders, and provide training and support to ensure a smooth transition. This step often requires strong leadership to guide the organization through the change.

  • Monitor and Evaluate

After implementation, continuously monitor the performance of the new processes against the established metrics and goals. Gather feedback from employees and customers to assess the effectiveness of the changes. Use this data to identify areas for further improvement and make necessary adjustments.

  • Continuous Improvement

BPR is not a one-time effort but a continuous process. Foster a culture of continuous improvement by regularly reviewing processes and seeking feedback. Encourage innovation and adaptability to ensure that the organization remains responsive to changing market conditions and customer needs.

Benefits of Business Process Reengineering:

  • Increased Efficiency

One of the most immediate benefits of BPR is improved efficiency. By re-evaluating and redesigning processes, organizations can eliminate redundant steps and streamline workflows. This leads to faster execution of tasks and better utilization of resources, resulting in lower operational costs.

  • Enhanced Quality

BPR focuses on identifying and rectifying process flaws, which can lead to higher quality products and services. By implementing standardized processes and best practices, organizations can reduce errors and improve consistency. Enhanced quality not only boosts customer satisfaction but also strengthens the organization’s reputation.

  • Greater Customer Satisfaction

BPR prioritizes customer needs by creating processes that are more responsive and tailored to client expectations. By reducing response times and improving service delivery, organizations can enhance the overall customer experience. Increased customer satisfaction fosters loyalty and can lead to repeat business and referrals.

  • Flexibility and Agility

In a dynamic business environment, the ability to adapt quickly is crucial. BPR enables organizations to design flexible processes that can easily accommodate changes in market conditions, customer demands, or technological advancements. This agility allows businesses to seize new opportunities and respond to challenges more effectively.

  • Cost Reduction

Through the elimination of inefficiencies and redundancies, BPR can lead to significant cost savings. Organizations can reduce labor costs, minimize waste, and optimize resource allocation. Lower operational costs improve the bottom line and enable reinvestment in growth initiatives.

  • Improved Employee Morale

Streamlined processes reduce frustration among employees caused by bureaucratic hurdles and inefficiencies. When employees work in an environment with clear, efficient processes, their productivity increases, leading to higher job satisfaction and morale. Engaged employees are more likely to contribute positively to the organization.

  • Innovation and Competitive Advantage

BPR encourages a culture of innovation by challenging existing practices and promoting creative thinking. Organizations that embrace BPR are more likely to identify new opportunities and develop innovative products or services. This focus on innovation can provide a significant competitive advantage in the marketplace.

Challenges of Business Process Reengineering:

  • Resistance to Change

One of the most significant hurdles in BPR is employee resistance. Many individuals are comfortable with established routines and may view changes as threats to their job security or work processes. Overcoming this resistance requires effective communication, involvement, and change management strategies to foster buy-in from all levels of the organization.

  • Lack of Clear Vision

BPR initiatives can falter without a clear vision and objectives. If the goals of the reengineering process are not well-defined or communicated, employees may lack direction, leading to confusion and ineffective implementation. Establishing a clear and compelling vision is essential for aligning efforts and motivating the team.

  • Insufficient Leadership Support

Successful BPR requires strong leadership commitment and support. Without active engagement from top management, initiatives may lack the necessary resources, authority, and visibility. Leaders must champion the change, provide direction, and demonstrate commitment to the reengineering process for it to gain traction.

  • Inadequate Training and Skills

Reengineering processes often require new skills and knowledge. If employees are not adequately trained to adapt to new systems, technologies, or workflows, the implementation can suffer. Organizations must invest in comprehensive training programs to equip employees with the skills needed to succeed in the transformed environment.

  • Complexity of Processes

Analyzing and redesigning complex processes can be overwhelming. Organizations may struggle to identify all variables and interdependencies within their existing workflows. This complexity can lead to incomplete assessments and poorly designed processes, undermining the effectiveness of the reengineering effort.

  • Scope Creep

BPR projects progress, there is a risk of scope creep, where the focus expands beyond the original objectives. This can lead to resource overextension, delays, and confusion about priorities. Organizations must maintain a disciplined approach, ensuring that the scope of the project remains focused and aligned with strategic goals.

  • Measurement and Evaluation Challenges

Measuring the success of BPR initiatives can be difficult. Organizations may struggle to define appropriate metrics or benchmarks to evaluate performance improvements effectively. Without clear metrics, it can be challenging to assess the impact of changes and make necessary adjustments, leading to potential stagnation or regression.

Factors Affecting Job Design

Job Design is an important function of Human Resource Management (HRM) that involves organizing tasks, duties, responsibilities, and activities to achieve organizational objectives efficiently. It determines how work is performed, how responsibilities are distributed, and how employees interact with their jobs. Effective job design helps improve employee productivity, job satisfaction, motivation, and organizational performance. However, job design is influenced by several factors that determine the nature and structure of different jobs. These factors include organizational objectives, technological developments, employee skills and abilities, employee motivation, the nature of the job, organizational structure, legal requirements, and working conditions. Organizations must carefully consider these factors while designing jobs to ensure that work requirements match employee capabilities and business needs. A well-designed job provides clarity of responsibilities, opportunities for skill development, and a suitable balance between efficiency and employee well-being. It also reduces work-related stress, improves coordination, and supports effective utilization of human resources. Therefore, understanding the factors affecting job design is essential for creating meaningful, productive, safe, and satisfying jobs that contribute to the long-term success of both employees and the organization.

Factors Affecting Job Design

1. Organizational Objectives

Organizational objectives are one of the most important factors affecting job design. Every job should be designed according to the goals, strategies, and priorities of the organization. If an organization focuses on productivity, jobs may emphasize efficiency and specialization. If it emphasizes innovation, employees may receive greater autonomy and opportunities for creativity. Job design must also support organizational growth, quality improvement, and customer satisfaction. Therefore, aligning jobs with organizational objectives helps ensure effective utilization of human resources and achievement of overall business goals.

2. Technological Factors

Technology significantly influences job design because modern machines, software, automation, and digital systems change the way work is performed. Advanced technology may reduce repetitive manual tasks and create jobs requiring technical knowledge and problem-solving skills. Employees may need training to operate new equipment and manage digital processes. Technology can also improve communication, flexibility, and efficiency. However, excessive automation may reduce certain job responsibilities. Therefore, organizations must design jobs that balance technological capabilities with human skills, employee involvement, and changing workplace requirements.

3. Employee Skills and Abilities

The skills, knowledge, qualifications, and abilities of employees are important considerations in job design. Jobs should match employees’ capabilities while providing opportunities to learn and develop. Highly skilled employees may perform complex tasks and take greater responsibility, whereas inexperienced employees may require simpler duties and supervision. Appropriate job design improves employee confidence, performance, and job satisfaction. It also helps organizations identify training requirements and develop employee potential. Matching job requirements with individual abilities reduces errors, improves efficiency, and supports better utilization of human resources.

4. Employee Motivation and Satisfaction

Employee motivation and job satisfaction influence the way jobs should be designed. Jobs that provide meaningful tasks, recognition, responsibility, autonomy, and opportunities for achievement generally encourage greater employee involvement. Repetitive and monotonous work may cause boredom, dissatisfaction, and reduced productivity. Organizations can improve job design through job enrichment, job enlargement, and job rotation. These approaches provide variety, responsibility, and learning opportunities. A well-designed job can increase employee commitment, reduce absenteeism, and improve retention by making work more interesting and rewarding.

5. Nature of the Job

The nature and complexity of the job directly affect its design. Different jobs require different levels of physical effort, mental ability, technical knowledge, decision-making, and responsibility. For example, managerial jobs involve planning, leadership, and decision-making, whereas production jobs may require technical operations and quality control. Job designers must consider the tasks to be performed, the working environment, and the expected outcomes. Properly understanding job characteristics helps establish suitable duties, responsibilities, authority, and performance standards, ensuring that employees can perform their work effectively.

6. Organizational Structure

The organizational structure influences job design by determining authority, reporting relationships, communication channels, and departmental responsibilities. In a centralized organization, employees may have limited decision-making authority and follow clearly defined instructions. In a decentralized organization, employees may receive greater autonomy and responsibility. Job design must also support coordination between departments and avoid unnecessary duplication of duties. Clearly defined reporting relationships improve accountability and communication. Therefore, job design should be consistent with the organizational structure to ensure smooth operations and effective coordination.

7. Legal and Safety Requirements

Labour laws, employment regulations, and workplace safety standards influence job design. Organizations must consider working hours, rest periods, employee welfare, equal employment opportunities, and applicable occupational health and safety requirements. Jobs involving machinery, hazardous materials, or physically demanding activities require appropriate safety measures and protective equipment. Employers must also ensure that job requirements are reasonable and comply with relevant legal obligations. Proper job design reduces workplace risks, prevents accidents, and protects employee well-being. It also helps organizations maintain lawful and responsible employment practices.

8. Working Environment and Conditions

The working environment and job conditions play an important role in determining job design. Factors such as temperature, lighting, noise, workspace, equipment, workload, and workplace relationships affect employee comfort and performance. A safe and comfortable environment helps employees concentrate and complete their tasks efficiently. Poor working conditions may lead to fatigue, stress, errors, and dissatisfaction. Job designers should consider ergonomic principles, suitable work schedules, and adequate resources. Improving working conditions promotes employee health, reduces workplace problems, and contributes to higher productivity and job satisfaction.

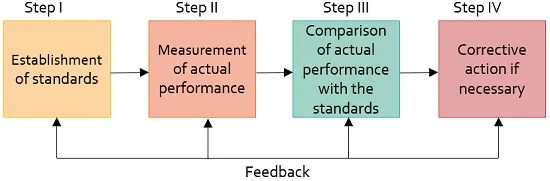
Steps in Control Process

Control in Management refers to the process of monitoring and evaluating performance against established standards and objectives. It involves setting performance benchmarks, measuring actual outcomes, comparing them with targets, and taking corrective actions as needed. The ultimate goal of control is to ensure that organizational activities align with strategic goals, thereby enhancing efficiency and effectiveness.

Control Process involves the following Steps as shown in the figure:

The control process involves several key steps:

  1. Establishing Standards

Standards serve as benchmarks for evaluating performance in business functions and are classified into two categories:

  • Measurable (Tangible) Standards: These standards are quantifiable and expressed in terms of cost, output, time, profit, etc.
  • Non-Measurable (Intangible) Standards: These cannot be quantified monetarily. Examples include manager performance, employee attitudes, and workplace morale.

Establishing these standards simplifies the control process, as control is exercised based on them.

  1. Measurement of Actual Performance

The second step is assessing actual performance levels to identify deviations from established standards. Measuring tangible standards is generally straightforward, as they can be quantified easily. However, evaluating intangible standards, such as managerial performance, can be challenging and may rely on factors like:

  • Employee attitudes
  • Workforce morale
  • Improvements in the work environment
  • Communication with superiors

Performance measurement may also be supported by various reports (weekly, monthly, quarterly, or yearly).

  1. Comparison of Actual Performance with Standards:

Comparing actual performance against planned targets is crucial. A deviation is defined as the gap between actual and planned performance. Managers need to identify two key aspects:

  • Extent of Deviation: Is the deviation positive, negative, or aligned with expectations?
  • Cause of Deviation: Understanding why deviations occurred is vital for effective management.

Managers should focus on critical deviations while overlooking minor ones. For instance, a 5-10% increase in stationery costs may be considered minor, whereas a continuous decline in monthly production signifies a major issue.

Common causes of deviations:

  • Faulty planning
  • Lack of coordination
  • Defective plan implementation
  • Ineffective supervision and communication
  1. Taking Corrective Actions

After identifying the extent and causes of deviations, managers must implement remedial measures. They have two options:

  1. Corrective Measures: Address the deviations that have already occurred.
  2. Revision of Targets: If the corrective actions do not align actual performance with planned targets, managers may choose to adjust the targets.

Controlling, Definition, Importance, Nature, Scope, Elements, Limitations

Controlling is a fundamental management function that involves monitoring organizational performance, comparing it against established standards, and taking corrective actions when necessary. It ensures that the organization’s activities align with its goals and objectives. The controlling process includes setting performance standards, measuring actual performance, and evaluating deviations from the standards. Effective controlling helps identify areas for improvement, ensures resource optimization, and enhances decision-making. By providing feedback on performance, controlling enables managers to make informed adjustments to strategies and operations, fostering efficiency and effectiveness in achieving organizational goals.

Definition of Controlling:

  • Henri Fayol:

Fayol, a pioneer in management theory, defined controlling as “the process of verifying whether everything occurs in conformities with the plan adopted, the instructions issued, and the principles established.” This emphasizes the alignment of actual performance with planned objectives.

  • George R. Terry:

Terry defined controlling as “the measurement of accomplishment against standards and the correction of deviation to ensure achievement of organizational objectives.” This highlights the evaluative aspect of controlling in relation to organizational goals.

  • Harold Koontz and Cyril O’Donnell:

They defined controlling as “the function of management which ensures that everything occurs in accordance with the standards established.” This definition stresses the importance of standards in the controlling process.

  • Peter Drucker:

Drucker defined controlling as “the process of measuring performance and taking corrective actions when necessary.” His focus is on performance measurement and the proactive nature of controlling.

  • Luther Gulick:

Gulick described controlling as “the function of management which ensures that organizational goals are met through appropriate actions.” This definition emphasizes the role of controlling in achieving organizational objectives.

  • American Management Association (AMA):

AMA defines controlling as “the process of establishing standards to achieve organizational goals, measuring actual performance against those standards, and taking corrective action when necessary.” This definition encapsulates the overall purpose of the controlling function.

  • Robert J. Mockler:

Mockler defined controlling as “the process of monitoring performance, comparing it with the established standards, and taking corrective action if necessary to ensure that the organization’s objectives are achieved.” This highlights the cyclical nature of controlling in the management process.

Importance of Controlling:

  • Ensures Goal Achievement:

The primary purpose of controlling is to ensure that organizational goals are met. By setting performance standards and measuring actual performance against these benchmarks, managers can identify deviations and take corrective actions, ensuring that the organization remains on track to achieve its objectives.

  • Enhances Efficiency:

Controlling helps to improve the efficiency of organizational processes. By monitoring operations, managers can identify bottlenecks, redundancies, and areas for improvement. This allows for the optimization of resource utilization, reducing waste and improving overall productivity.

  • Facilitates Decision-Making:

Effective controlling provides managers with relevant and timely information about performance. This information is critical for informed decision-making. Managers can analyze trends, identify problems, and evaluate the effectiveness of different strategies, enabling them to make better decisions that align with organizational goals.

  • Promotes Accountability:

Control systems establish clear expectations and performance standards for employees. This promotes accountability, as individuals are aware of the metrics against which their performance will be evaluated. When employees understand that their work is being monitored, they are more likely to take ownership of their responsibilities and strive to meet performance standards.

  • Encourages Continuous Improvement:

Controlling fosters a culture of continuous improvement within the organization. Regular performance assessments and feedback mechanisms encourage employees to seek ways to enhance their work processes, leading to innovation and higher quality outcomes. This proactive approach contributes to long-term organizational success.

  • Identifies Problems Early:

Through ongoing monitoring and evaluation, controlling enables managers to identify potential issues before they escalate into significant problems. Early detection allows for timely interventions, minimizing the impact on operations and helping to maintain organizational stability.

  • Facilitates Coordination:

Controlling ensures that different departments and teams within the organization are working harmoniously toward common goals. By monitoring interdependencies and ensuring that performance aligns with overall objectives, controlling promotes coordination and cooperation among various organizational units.

  • Provides a Basis for Future Planning:

The information gathered during the controlling process serves as valuable input for future planning. By analyzing performance data, managers can assess the effectiveness of previous strategies, identify trends, and make informed projections for the future. This alignment between past performance and future planning helps organizations remain agile and responsive to changing circumstances.

Nature of Controlling:

  • Goal-Oriented:

Controlling is fundamentally concerned with achieving organizational goals. It involves setting performance standards that align with these goals and continuously monitoring progress toward their attainment. By focusing on objectives, controlling ensures that all activities are directed towards fulfilling the organization’s mission.

  • Continuous Process:

Controlling is an ongoing process that occurs throughout the life of an organization. It involves regular monitoring and evaluation of performance, enabling managers to identify deviations and take corrective actions as needed. This continuous nature ensures that organizations remain adaptable to changes and can maintain effective performance.

  • Feedback Mechanism:

One of the critical functions of controlling is to provide feedback on performance. By comparing actual performance with established standards, managers can assess whether goals are being met. This feedback loop is essential for identifying areas for improvement and making informed decisions regarding resource allocation and operational adjustments.

  • Dynamic Function:

Controlling is not a static function; it evolves with the organization and its environment. As organizations face new challenges and opportunities, the controlling process must adapt to reflect changes in strategies, technologies, and market conditions. This dynamism ensures that controlling remains relevant and effective in guiding organizational performance.

  • Involves Decision-Making:

Controlling is closely linked to decision-making processes. Managers must analyze performance data, interpret results, and make decisions about corrective actions when performance deviates from standards. This aspect highlights the importance of analytical skills and judgment in effective controlling, as managers must be able to determine the best course of action based on performance assessments.

  • Universal Applicability:

The principles of controlling apply to all types of organizations, regardless of size or industry. Whether in manufacturing, services, or non-profit sectors, controlling is essential for ensuring that organizational activities are aligned with strategic objectives. This universality underscores the importance of controlling as a core function of management.

  • Emphasizes Efficiency and Effectiveness:

The primary aim of controlling is to enhance organizational efficiency and effectiveness. By monitoring processes and performance, organizations can optimize resource use and improve productivity. Effective controlling helps identify waste, streamline operations, and ensure that activities are conducted in the most efficient manner possible, ultimately contributing to organizational success.

Scope of Controlling:

  • Performance Measurement:

One of the primary scopes of controlling is to measure the actual performance of employees, departments, and the organization as a whole. This involves establishing performance standards and metrics, collecting data on actual performance, and comparing it with the set standards. Performance measurement provides insights into how well an organization is functioning and identifies areas that require improvement.

  • Deviation Analysis:

Controlling involves analyzing deviations between actual performance and planned performance. When discrepancies arise, managers must determine the causes of these deviations. This analysis helps in understanding whether the deviations are due to external factors, such as market conditions, or internal factors, such as operational inefficiencies. By identifying the root causes, organizations can implement corrective actions to address the issues.

  • Corrective Actions:

Based on the analysis of deviations, controlling encompasses the development and implementation of corrective actions. These actions are designed to realign actual performance with established standards and objectives. Corrective measures may include changes in processes, resource reallocation, or additional training for employees. The goal is to ensure that the organization remains on track to achieve its goals.

  • Resource Management:

Controlling plays a critical role in managing organizational resources effectively. This includes financial resources, human resources, and physical assets. By monitoring resource utilization and efficiency, managers can ensure that resources are allocated appropriately, minimizing waste and maximizing productivity. Effective resource management contributes to the overall effectiveness of the organization.

  • Budgetary Control:

A significant aspect of controlling is budgetary control, which involves monitoring the organization’s financial performance against budgeted figures. Managers use budgetary controls to assess spending, revenue generation, and profitability. By analyzing variances between budgeted and actual figures, managers can make informed financial decisions and adjust budgets as necessary to meet organizational objectives.

  • Quality Control:

Controlling also encompasses quality control measures to ensure that products and services meet established quality standards. This includes implementing processes for inspecting and testing outputs, as well as continuous improvement initiatives. Quality control helps organizations maintain high standards, enhance customer satisfaction, and reduce costs associated with defects and rework.

  • Strategic Control:

Controlling extends to strategic control, which involves monitoring the organization’s progress toward achieving its long-term goals and strategic objectives. This includes assessing the effectiveness of strategies, evaluating competitive positioning, and ensuring that the organization adapts to changing market conditions. Strategic control helps organizations remain proactive and responsive in a dynamic business environment.

Elements of Controlling:

  • Setting Performance Standards

The first step in controlling is setting clear and measurable performance standards. These standards serve as a benchmark for evaluating actual performance. They may be quantitative (e.g., sales targets, production levels) or qualitative (e.g., customer satisfaction, employee engagement). Performance standards should be realistic, achievable, and aligned with organizational goals.

  • Measuring Actual Performance

Once performance standards are set, it is essential to measure actual performance. This involves collecting data, tracking results, and monitoring activities to evaluate whether targets are being met. The methods of measurement can vary, such as financial reports, production logs, or customer feedback, depending on the nature of the performance standards.

  • Comparing Actual Performance with Standards

After measuring actual performance, it is compared with the established performance standards. This step helps identify any variances between planned and actual outcomes. If the actual performance exceeds or meets the standards, it indicates success. If there is a shortfall, corrective actions will be needed to bring performance in line with the targets.

  • Analyzing Deviations

When deviations from the set standards are identified, it is important to analyze the causes. These deviations may occur due to various factors such as external influences (market changes, economic conditions), internal inefficiencies (lack of resources, poor management), or human factors (motivation, skills). A thorough analysis of the reasons behind the deviations helps in deciding the appropriate corrective measures.

  • Taking Corrective Actions

Once the reasons for deviations are analyzed, corrective actions should be taken. These actions aim to eliminate the causes of deviations and bring performance back on track. Corrective actions can involve adjusting strategies, reallocating resources, modifying processes, or enhancing employee training. The effectiveness of corrective actions should also be monitored to ensure continuous improvement.

  • Feedback and Adjustments

The final element of controlling is the feedback loop. After taking corrective actions, it’s crucial to gather feedback to assess their effectiveness. Based on feedback, further adjustments may be needed. Continuous monitoring and adjustment ensure that performance standards are kept relevant and that the organization stays on course to achieve its objectives.

Limitations of Controlling:

  • Inflexibility:

Controlling can lead to rigidity in an organization. Overemphasis on control mechanisms may result in inflexible procedures, stifling creativity and innovation. Employees may feel constrained by strict guidelines and metrics, which can hinder their ability to adapt to changing circumstances or propose new ideas.

  • Costly Process:

Implementing a comprehensive control system can be expensive. The costs associated with setting up control measures, monitoring performance, and conducting audits can strain organizational resources. Small businesses, in particular, may find it challenging to allocate sufficient funds for effective control systems.

  • Time-Consuming:

The controlling process can be time-consuming. Collecting data, analyzing performance, and implementing corrective actions require considerable time and effort from managers and employees. This time investment may distract from other critical activities and delay decision-making processes.

  • Subjectivity in Evaluation:

Controlling often involves subjective judgment in performance evaluation. Managers may rely on their interpretations of data, which can lead to bias and inconsistencies in assessing employee performance. This subjectivity can create misunderstandings, conflicts, and decreased morale among staff.

  • Limited Scope:

Control systems may focus primarily on quantitative measures, neglecting qualitative factors such as employee satisfaction, teamwork, and organizational culture. A narrow focus on numbers can overlook important aspects of performance that contribute to overall success.

  • Resistance to Control:

Employees may resist control measures due to perceived threats to their autonomy and job security. This resistance can result in a lack of cooperation, reduced morale, and a negative organizational climate. Overly strict control measures can lead to disengagement and decreased productivity among staff.

  • Delayed Feedback:

In some cases, feedback from control systems may be delayed, making it challenging to address issues promptly. If performance data is not available in real-time, managers may miss opportunities to make timely corrections, allowing problems to escalate.

  • Overreliance on Control Systems:

Organizations may become overly dependent on control systems, leading to a lack of initiative and accountability among employees. When individuals feel that their work is constantly monitored, they may become less proactive and less willing to take risks, ultimately affecting overall performance.

Management by Exception (MBE), Steps, Advantages and Limitations

Management by Exception (MBE) is a management approach where leaders focus on significant deviations from set standards or expected outcomes, rather than on routine operations. Managers intervene only when performance significantly deviates from targets, either exceeding or falling short of expectations. This allows them to concentrate on critical issues that require attention, while routine matters are handled by subordinates. MBE improves efficiency by reducing the time managers spend on day-to-day activities and encourages employee autonomy. It ensures effective resource allocation and quick response to major problems or opportunities.

Steps of Management by Exception (MBE):

  1. Set Clear Objectives and Performance Standards

The first step in MBE is to establish clear organizational goals and performance standards. These benchmarks provide a basis for evaluating results and identifying exceptions. The standards must be measurable, relevant, and aligned with the company’s strategic objectives. Employees should be well-informed about these expectations to ensure understanding and compliance.

  1. Measure Actual Performance

Once the objectives and standards are set, managers need to continuously monitor and measure actual performance. This involves collecting data from various sources, such as reports, audits, or performance reviews, to ensure accurate and timely measurement of employee or departmental outputs. The performance data should be transparent and easily accessible to facilitate ongoing monitoring.

  1. Compare Performance Against Standards

In this step, managers compare the measured performance against the set standards. The goal is to identify any significant deviations that require attention. This comparison helps determine whether performance is on track or if there are substantial differences that necessitate intervention.

  1. Identify Exceptions

Managers focus only on deviations that are significant enough to be considered exceptions. These exceptions could be positive, such as exceeding sales targets, or negative, such as underperforming in a key area. Identifying exceptions helps managers concentrate on the most critical areas, while routine matters are handled by employees.

  1. Analyze the Cause of Exceptions

Once exceptions are identified, managers analyze the underlying causes of the deviations. This involves investigating whether the exception was caused by internal factors, such as inadequate resources or poor planning, or external factors, such as market changes. Understanding the root cause is essential for developing appropriate corrective actions.

  1. Take Corrective Action

After identifying the cause of exceptions, managers take corrective action to resolve the issue. The nature of the corrective action will depend on the severity and type of deviation. It could involve reallocating resources, providing additional training, revising strategies, or making adjustments to the performance standards.

  1. Monitor Results of Corrective Action

Once corrective measures are implemented, the next step is to monitor the results to ensure the actions have successfully addressed the exception. This continuous monitoring helps prevent future deviations and ensures that the organization remains on track toward achieving its goals.

  1. Review and Adjust Standards (if necessary)

In some cases, the performance standards themselves may need adjustment. If the deviation is not due to employee performance but rather unrealistic or outdated standards, managers may need to revise the objectives or benchmarks to reflect changing circumstances. This step ensures that the standards remain relevant and achievable.

Advantages of Management by Exception (MBE):

  1. Efficient Use of Managerial Time

One of the primary advantages of MBE is that it saves time for managers by allowing them to focus on critical issues instead of routine matters. Managers only step in when performance deviates significantly from the plan, which frees them from constantly micromanaging every aspect of operations. This selective attention helps in better time management and ensures that their focus is directed where it is most needed.

  1. Promotes Employee Autonomy

MBE encourages employees to take responsibility for day-to-day operations, as managers intervene only when necessary. Employees gain autonomy over routine tasks, which can boost their confidence, decision-making abilities, and job satisfaction. This empowerment of employees leads to increased accountability and promotes a sense of ownership over their work.

  1. Encourages Better Decision-Making

Since MBE focuses on exceptions or significant deviations, it ensures that managerial attention is drawn to issues that require immediate decision-making. This system of management helps managers make quicker and more informed decisions about critical matters, leading to timely corrective actions. It also helps in prioritizing the most pressing concerns, thus improving overall decision-making efficiency.

  1. Increased Productivity

By allowing employees to handle regular tasks independently and focusing managerial attention on significant issues, MBE can enhance productivity. Managers are not bogged down by routine matters and can concentrate on strategic activities, which in turn improves overall organizational efficiency. This division of focus also ensures that employees perform their tasks with minimal supervision, leading to a smoother workflow.

  1. Reduction in Information Overload

MBE reduces the burden of information overload for managers. Since they are only required to intervene when performance falls outside established norms, they receive fewer reports and updates about routine activities. This selective information flow allows managers to concentrate on critical reports, reducing unnecessary data handling and simplifying decision-making.

  1. Effective Resource Allocation

By focusing on significant deviations from the norm, MBE ensures that resources—both human and financial—are allocated efficiently. Managers can direct resources towards solving key issues or seizing important opportunities, rather than wasting them on minor adjustments. This strategic allocation of resources helps in optimizing organizational performance.

  1. Improved Control Mechanism

MBE establishes a clear control mechanism by setting performance standards and monitoring outcomes. Managers can quickly identify areas of concern and take corrective actions when deviations occur. This ensures that problems are addressed before they escalate, maintaining better control over operations and ensuring adherence to goals and policies.

  1. Encourages Focus on Strategic Issues

Since MBE directs managerial attention to exceptions, it ensures that managers focus on strategic issues that require intervention. This ability to concentrate on important matters allows for more effective long-term planning, risk management, and opportunity exploitation. It aligns managerial efforts with the organization’s strategic objectives, promoting growth and competitiveness.

Limitations of Management by Exception (MBE):

  1. Overlooking Minor issues

MBE’s focus on significant deviations can lead to the neglect of minor problems that, if left unresolved, may escalate into larger issues. These small discrepancies might seem insignificant but can compound over time, eventually affecting overall performance or creating inefficiencies in processes.

  1. Delayed Managerial Intervention

One of the potential downsides of MBE is that by waiting for deviations to become significant, managers may respond too late. This delay in intervention might cause problems to worsen before they are addressed. Timely management involvement is crucial, but MBE may cause managers to overlook issues until they require immediate attention.

  1. Dependence on Pre-Established Standards

MBE relies heavily on pre-established performance standards or benchmarks. If these standards are outdated or inappropriate, the entire system of exception management may fail. Poorly set benchmarks can lead to either excessive managerial intervention or insufficient control over processes.

  1. Employee Demotivation

Employees may feel demotivated or neglected under MBE, as managers only step in when there are issues. Without consistent feedback and engagement, employees might feel undervalued or ignored. This can reduce motivation and lower job satisfaction, ultimately affecting overall productivity.

  1. Limited Managerial Involvement in Daily Operations

MBE encourages minimal involvement in routine operations. While this can increase efficiency, it also means that managers might lose touch with day-to-day activities. Lack of involvement in operational matters could result in managers being disconnected from the realities faced by employees, leading to ineffective decision-making when intervention is required.

  1. Potential for Over-Reliance on Technology

In many MBE systems, technology is used to monitor performance and detect deviations. This reliance on technology can create issues if the systems fail or produce inaccurate data. Over-reliance on technology may also lead to a reduction in the human element of management, weakening the ability to understand the nuances of workplace dynamics.

  1. Reactive Rather than Proactive Management

MBE is inherently reactive, meaning that managers wait for problems to arise before acting. This reactive approach can hinder the organization’s ability to proactively address potential risks or exploit emerging opportunities. Being proactive is essential for long-term success, but MBE may limit this forward-thinking capability.

  1. Challenges in Defining “Exception”

Determining what constitutes a significant exception can be challenging. Different departments or managers may have varying thresholds for what they consider an exception, leading to inconsistency in when interventions are triggered. This inconsistency can create confusion and reduce the effectiveness of MBE.

  1. Stifling Innovation

MBE’s emphasis on conformity to standards may stifle creativity and innovation. Employees may focus solely on meeting established benchmarks, avoiding risks or new ideas to prevent deviations. This could limit opportunities for improvement and hinder the organization’s ability to innovate and adapt to changing environments.

Control, Meaning, Definition, Types, Process and Requirements for Effective Control

Control is an important function of management concerned with ensuring that organizational activities are performed according to planned objectives and standards. It involves measuring actual performance, comparing it with predetermined standards, identifying deviations, and taking corrective action when necessary. Control helps managers determine whether plans are being properly implemented and whether organizational resources are being used efficiently. It is closely related to planning, because control evaluates actual performance against planned performance. Effective control does not merely identify mistakes; it also helps prevent future deviations and improve organizational performance. Therefore, control ensures that managerial efforts remain directed toward achieving organizational goals.

Definition of Control

Control has been defined by different management thinkers in various ways:

  • Henry Fayol: “Control consists in verifying whether everything occurs in conformity with the plan adopted, the instructions issued and principles established.”
  • Koontz and O’Donnell: Control is the measurement and correction of performance in order to ensure that enterprise objectives and plans devised to attain them are accomplished.
  • George R. Terry: Control is determining what is being accomplished, evaluating the performance, and, if necessary, applying corrective measures so that performance takes place according to plans.

Types of Control

  • Feed-Forward Controls

These controls are proactive, aiming to identify and address potential problems before they arise. They can be diagnostic (indicating what has deviated from standards) or therapeutic (explaining why deviations occurred and recommending corrective actions).

  • Concurrent (Prevention) Control

This type of control allows for adjustments during an ongoing process. By establishing clear job descriptions and specifications, concurrent controls prevent errors before they happen, improving overall efficiency.

  • Feedback Controls

Feedback controls are historical and assess performance after the fact. They focus on end results and provide information for future activities to avoid repeating past mistakes.

Controlling Process in Business Management

  • Setting Performance Standards

The first step involves establishing benchmarks for measuring actual performance, which can be quantitative (e.g., revenue targets) or qualitative (e.g., improving employee motivation).

  • Measurement of Actual Performance

After setting standards, actual performance is measured using various techniques, such as performance reports, financial ratios, and direct observation.

  • Comparing Actual Performance with Standards

This step involves evaluating actual results against the established standards to identify any deviations.

  • Analyzing Deviations

Significant deviations warrant urgent management attention, while minor deviations can be addressed later. Techniques such as critical point control and management by exception are useful in this phase.

  • Taking Corrective Action

If deviations exceed acceptable limits, management must implement corrective measures to align performance with standards, focusing particularly on critical areas that impact overall business success.

Control Techniques

Control Techniques are methods used by managers to ensure that organizational goals are achieved effectively and efficiently. They involve measuring actual performance against established standards, identifying deviations, and implementing corrective actions. Common control techniques include direct supervision, financial analysis, budgetary control, and management information systems. These techniques help organizations monitor operations, assess performance, and make informed decisions, ultimately facilitating continuous improvement and ensuring that objectives are met within the desired timeframe and resource constraints.

Types of Control Techniques

  • Direct Supervision and Observation

This is the oldest technique of controlling, where supervisors observe employees directly during their work. This method allows supervisors to address issues in real-time and gain firsthand insights into employee performance. It’s particularly effective in small businesses where close interaction is feasible.

  • Financial Statements

Organizations prepare Profit and Loss Accounts and Balance Sheets to summarize financial performance over specific periods. These statements help compare current figures with previous years and facilitate ratio analysis, which assesses profitability, liquidity, and solvency.

  • Budgetary Control

Budgetary control involves the establishment of budgets for various business aspects, including income, expenditures, production, and capital. It serves as a managerial control tool, enabling businesses to monitor financial performance against planned budgets.

  • Break-Even Analysis

Break-Even Analysis identifies the point at which total revenues equal total costs, meaning no profit or loss is incurred. By determining this point, businesses can assess performance and make necessary adjustments to improve future outcomes.

  • Return on Investment (ROI)

ROI measures the profitability of investments in fixed assets and working capital. A high ROI indicates strong financial performance, while a low ROI highlights areas needing improvement. It allows for performance comparisons over time and between firms.

  • Management by Objectives (MBO)

MBO is a collaborative process where objectives are set jointly by superiors and subordinates. It includes periodic evaluations and feedback, ensuring that individual performances are assessed against established goals, which can lead to rewards for achievement.

  • Management Audit

Management audit evaluates the entire management process, including planning, organizing, directing, and controlling. Conducted by experts, it assesses efficiency by analyzing plans, objectives, policies, and procedures, providing insights into managerial performance.

  • Management Information System (MIS)

MIS collects and processes accurate information about internal operations and external environments. By providing managers with relevant data, it supports informed decision-making and allows for effective delegation without losing control.

  • PERT and CPM Techniques

Program Evaluation and Review Technique (PERT) and Critical Path Method (CPM) focus on the sequential completion of activities within a project. These techniques help manage time and resources effectively, ensuring timely project completion.

  • Self-Control

Self-control empowers individuals to set their own targets and evaluate their performance independently. While it’s crucial for top-level managers, subordinates should also be encouraged to adopt self-control to reduce the burden of constant oversight by superiors.

Requirements for Effective Control

1. Clear Objectives and Standards

Effective control requires clearly defined organizational objectives and performance standards. Managers must know what results are expected before actual performance can be measured. Standards should be specific, realistic, measurable, and related to organizational goals. Clear standards provide a basis for comparing actual performance and identifying deviations. They also help employees understand the level of performance expected from them. Without proper standards, control becomes uncertain and managers may find it difficult to determine whether activities are progressing satisfactorily.

2. Accurate and Reliable Information

Effective control depends on accurate, relevant, and reliable information about organizational performance. Managers need timely information regarding production, sales, costs, employee performance, quality, and other important activities. Incorrect or incomplete information can lead to inappropriate decisions and ineffective corrective action. Therefore, organizations should establish reliable reporting and information systems. Proper information enables managers to identify deviations accurately and take suitable action before problems become serious.

3. Timely Reporting

Control should provide timely information and reports to managers. Information received too late may lose its usefulness because corrective action may no longer be effective. Managers should receive performance reports at appropriate intervals depending on the nature of the activity. For example, critical production activities may require frequent monitoring, while routine activities may be reviewed periodically. Timely reporting enables management to identify problems quickly and respond before deviations significantly affect organizational performance.

4. Flexibility

An effective control system should be flexible enough to adjust to changes in organizational conditions. Business environments may change because of technology, competition, customer preferences, economic conditions, or government policies. Rigid control systems may become unsuitable when circumstances change. Managers should therefore be able to modify standards, procedures, and methods when necessary. Flexible control enables organizations to respond to changing conditions while continuing to maintain appropriate performance standards.

5. Economy and Cost Effectiveness

The control system should be economical and cost-effective. The cost of establishing and operating control mechanisms should not exceed the benefits obtained from them. Organizations should concentrate control efforts on important activities where deviations can significantly affect performance. Excessive monitoring can waste time, money, and managerial resources. An economical control system provides useful information and effective supervision while keeping administrative costs within reasonable limits.

6. Simplicity

An effective control system should be simple and easy to understand. Employees and managers should be able to understand the standards, procedures, reports, and methods used for controlling performance. Complicated control systems may create confusion, increase administrative work, and reduce employee cooperation. Simple procedures make it easier to identify deviations and take corrective action. Therefore, control mechanisms should be designed according to the organization’s size, activities, and managerial requirements.

7. Focus on Critical Areas

Effective control requires managers to concentrate on critical areas and significant deviations. It is not practical or necessary to monitor every activity with the same level of attention. Managers should identify key areas where performance has a major effect on organizational objectives, such as costs, quality, productivity, sales, and customer satisfaction. The exception principle can be applied by giving greater attention to significant deviations. This allows managers to use their time and resources efficiently.

8. Corrective Action

The purpose of control is not simply to identify deviations but to ensure appropriate corrective action. When actual performance differs significantly from standards, managers should determine the causes and take suitable measures. Corrective action may involve changing methods, reallocating resources, providing employee training, revising schedules, or modifying plans. A control system is effective only when identified problems lead to meaningful improvements in performance and help the organization return toward its planned objectives.

Organizing, Principles, Nature, Significance, Limitations

Organizing is a fundamental management function that involves arranging resources and activities in a structured way to achieve the organization’s objectives efficiently. It includes identifying and grouping tasks, assigning roles, delegating authority, and allocating resources. Through organizing, a clear framework is established that defines the responsibilities and relationships within the organization, ensuring that all efforts are coordinated toward common goals. This process helps streamline operations, improve communication, and enhance the overall effectiveness of the workforce by aligning human, financial, and material resources with the organization’s strategy.

Principles of Organizing:

Principles of Organizing serve as guidelines for managers to structure resources and activities effectively within an organization. These principles ensure that the organization operates efficiently and achieves its objectives.

  1. Division of Work

This principle involves breaking down tasks into smaller, manageable activities. Specialization allows employees to focus on specific tasks, improving productivity and efficiency.

  1. Unity of Command

Each employee should report to only one superior to avoid confusion, overlapping instructions, and conflicts, ensuring clear accountability.

  1. Unity of Direction

All activities related to the same goal should be directed by one manager using one plan. This ensures that the team works toward the same objectives in a coordinated manner.

  1. Authority and Responsibility

Authority is the right to make decisions and issue commands, while responsibility is the obligation to carry out duties. There must be a balance between the two, with authority aligned with responsibility for efficient functioning.

  1. Delegation of Authority

Delegation involves assigning tasks and granting the necessary authority to subordinates. Proper delegation allows managers to focus on higher-level tasks, while empowering subordinates to make decisions.

  1. Chain of Command

The chain of command is the clear line of authority within an organization, from the top management to the lowest ranks. It establishes communication channels and maintains order.

  1. Span of Control

This principle defines the number of subordinates that a manager can effectively oversee. A manageable span of control helps ensure better supervision and communication.

  1. Coordination

Organizing involves aligning all efforts and resources within an organization to ensure smooth collaboration between departments and employees, preventing conflicts and duplication of efforts.

  1. Flexibility

The organizational structure should be flexible enough to adapt to changes in the environment, allowing the organization to respond efficiently to new challenges and opportunities.

  1. Scalar Principle

There should be a clear and direct line of authority from the top management to every individual at the bottom of the hierarchy, ensuring that decisions and instructions flow seamlessly.

  1. Simplicity

The organizational structure should be simple and easy to understand, avoiding unnecessary complexity that could lead to confusion and inefficiency.

  1. Balance

There must be a balance between centralization and decentralization. Some decisions should be made at higher levels, while others can be delegated to lower levels, ensuring effective control and operational flexibility.

Nature of Organizing:

  1. Goal-Oriented Process

Organizing is inherently a goal-oriented process. The primary purpose of organizing is to arrange resources and activities in a way that helps the organization achieve its objectives. It involves identifying what needs to be done, how tasks will be grouped, and how resources will be allocated to accomplish specific goals. Without clear goals, the organizing function loses direction.

  1. Specialization and Division of Labour

One of the defining characteristics of organizing is the division of labor and specialization. This concept involves breaking down the overall work into smaller, manageable tasks, each assigned to individuals or departments based on their expertise. Specialization leads to increased efficiency, as employees can focus on specific tasks in which they excel, fostering greater productivity and quality.

  1. Hierarchy and Authority

Organizing establishes a clear hierarchy within the organization, defining roles, responsibilities, and lines of authority. This hierarchy ensures that there is a well-defined chain of command, allowing for proper communication, delegation of tasks, and control. The hierarchical structure promotes accountability, as every individual knows their responsibilities and to whom they are accountable.

  1. Coordination of Efforts

Organizing also focuses on coordinating the efforts of different departments and individuals to ensure that the organization functions harmoniously. Without coordination, different units may work in isolation, leading to inefficiencies, duplication of efforts, and potential conflicts. A well-organized structure ensures that all parts of the organization are aligned toward common objectives and work in unison.

  1. Flexibility

While organizing creates a structured framework for the organization, it must also be flexible enough to adapt to changing conditions. Businesses operate in dynamic environments where market conditions, technology, and customer needs can change rapidly. A rigid structure may hinder an organization’s ability to respond effectively to new challenges. Flexibility ensures that the organization can reorganize resources, roles, and processes when necessary to stay competitive.

  1. Delegation of Authority

Delegation is a crucial part of organizing. Managers cannot do everything themselves, so they need to delegate tasks and authority to subordinates. Delegation involves giving others the responsibility and authority to perform certain tasks, allowing managers to focus on more strategic activities. It promotes empowerment and accountability at different levels within the organization.

Significance of Organizing:

  1. Efficient Resource Utilization

Organizing helps in the optimal allocation and use of resources, including human, financial, and material assets. By dividing work into specific tasks and assigning these tasks to the right people or departments, organizing ensures that resources are used in the most productive manner. This prevents wastage, reduces duplication of efforts, and maximizes output, ensuring that resources contribute directly to achieving organizational goals.

  1. Clear Hierarchy and Structure

Organizing creates a well-defined structure within the organization, establishing clear lines of authority, roles, and responsibilities. This hierarchy ensures that every employee knows their position in the organizational framework, who they report to, and their specific duties. Clear authority and accountability prevent confusion, enhance coordination, and streamline decision-making processes, resulting in smoother operations.

  1. Improves Communication

Effective organizing promotes clear communication within the organization. With clearly defined roles, responsibilities, and relationships, the flow of information becomes more structured. Organizing facilitates vertical and horizontal communication, ensuring that important information reaches the right people on time. This reduces misunderstandings and fosters better coordination between departments and teams.

  1. Facilitates Coordination

One of the primary objectives of organizing is to ensure that all departments, teams, and individuals work in harmony to achieve common goals. Organizing brings together various efforts by coordinating tasks and resources. It aligns the activities of different units, ensuring that they do not operate in isolation or at cross-purposes. This coordination is essential for avoiding duplication of efforts and achieving efficiency in operations.

  1. Promotes Specialization

Through division of labor and specialization, organizing ensures that individuals focus on tasks suited to their skills and expertise. This specialization enhances proficiency, reduces learning time, and increases the overall quality of work. By assigning tasks based on skills, organizing improves job performance and satisfaction, as employees are better able to contribute effectively.

  1. Flexibility and Adaptability

Organizing provides a flexible structure that can be adjusted according to changing business environments. An effective organizing system allows an organization to respond quickly to market changes, new technologies, and external challenges by reallocating resources, modifying roles, and introducing new processes. This adaptability is essential for staying competitive in a dynamic market.

  1. Fosters Growth and Innovation

A well-organized structure encourages innovation and business expansion. By ensuring clear responsibilities and efficient coordination, organizing frees up time for managers and employees to focus on creative thinking and long-term planning. A flexible and structured environment supports experimentation and the development of new ideas, contributing to the organization’s overall growth and success.

Limitations of Organizing:

  1. Inflexibility

One of the major limitations of organizing is the rigid structure it can create. Once roles, responsibilities, and hierarchies are established, it can be challenging to make adjustments. This rigidity makes it difficult for the organization to adapt quickly to changes in the business environment, such as shifts in customer preferences, new technologies, or market conditions.

  1. Over-Specialization

While specialization leads to efficiency, over-specialization can cause problems. When tasks are divided too narrowly, employees may become too focused on their specific roles, losing sight of the broader organizational goals. This narrow focus can result in a lack of innovation, reduced flexibility, and difficulty in adapting to new responsibilities outside their specialization.

  1. Coordination Challenges

Although organizing aims to promote coordination, in large and complex organizations, ensuring effective coordination between various departments and teams can be a significant challenge. Different units may have conflicting objectives, creating silos that prevent smooth communication and collaboration. This misalignment can slow down decision-making and lead to inefficiencies.

  1. High Costs

Organizing can sometimes lead to increased costs, particularly when an organization expands or adopts a more complex structure. Costs may arise from the need for more management personnel, more detailed systems of communication, and increased overheads related to maintaining coordination and control across various departments.

  1. Difficulties in Delegation

Effective organizing requires proper delegation of authority. However, in practice, many managers struggle to delegate tasks effectively, either because they are reluctant to give up control or because subordinates may lack the necessary skills. Poor delegation can lead to inefficiencies, overburdening managers and underutilizing the potential of lower-level employees.

  1. Conflict of Authority

In some cases, organizing can lead to confusion about who holds authority in specific situations. When roles and responsibilities overlap, conflicts may arise between managers and employees regarding decision-making power. This can lead to power struggles and hamper the overall efficiency of the organization.

  1. Slow Decision-Making

A well-organized structure often comes with layers of hierarchy. While hierarchy is essential for clarity, it can also slow down decision-making, as decisions may need to pass through multiple levels of approval. This can be particularly problematic in fast-moving industries where quick decisions are critical.

  1. Resistance to Change

Employees and managers often become accustomed to their roles and responsibilities within a particular organizational structure. When changes in the structure are necessary, such as during restructuring or reorganization, resistance to change can emerge. This resistance can slow down the transition process and hinder the organization’s ability to adapt.

  1. Lack of Innovation

An overly rigid organizational structure can stifle creativity and innovation. When employees are confined to specific roles with limited cross-functional interaction, they may have fewer opportunities to share new ideas or explore innovative approaches. This can hinder the organization’s ability to develop new products, services, or processes.

error: Content is protected !!