Fixed capital

The expression ‘fixed capital’ often considered to be analogous to ‘fixed assets’ denotes the employment of capital in permanent assets and other non-current assets. The fixed assets are assets of a permanent nature that the business does not intend to dispose of, or that could not be disposed of without interfering with the operation of the business.

The investment in the fixed assets is the first initial step in establishing a corporation. The investment in non-current assets is also called fixed capital. Such assets include items in which capital is locked up for a long period.

Although they do not indicate the investment in physical productive facilities, yet they are necessary for the conduct of the business and considered essential part of the capital arrangement.

They include long-term receivables, advances to subsidiary or affiliate companies, goodwill, patents, copyrights, long term investment in other companies and pre-paid expenses.

Thus the fixed assets are held by a company with the object of earning revenue directly or indirectly and not for the purpose of sale in the ordinary course of business. The fixed assets include land, buildings, plant, machinery and other fixed equipment, furniture and fixtures, vehicles, livestock etc.

Some definitions of fixed capital:

“Fixed capital is the funds required for the acquisition of those assets that are to be used over for a long period- such assets as land, buildings, machinery, equipment and tools.” :Shubin

“Fixed Capital comprises of fixed assets and other non-current assets”:F.N. Chiumiriatoo

“Fixed capital is invested in the fixed or long-run assets. The amount of fixed capital need, therefore, varies directly with the amount of fixed assets owned or used by a business.” :Wheeler

“Fixed capital is comparatively easily defined to include land, buildings, machinery and other assets having a relatively permanent existence.” -Hoagland

From the analysis of the above definitions, it is clear that fixed capital consists of investment in permanent assets which are necessary for conducting the operations and expansion of a business unit. Thus, fixed capital is used for meeting the permanent requirements of a business enterprise. It is the capital which is invested in fixed assets and non-current assets to generate profits for a company.

Importance of Fixed Capital:

Fixed capital plays a vital role in the establishment of business enterprises. It is required for acquiring fixed (tangible and intangible) assets, which is the preliminary requirement for starting a company. There are certain enterprises (manufacturing and public utilities) which cannot think of running in the absence of adequate amount of fixed capital.

Fixed capital is not only required for financing the acquisition of fixed assets, but also for initial period of its working in order to establish itself. It is also needed for making improvements and expanding the existing set up of a business enterprise. Thus, it appears that adequate amount of fixed capital is an essential pre-requisite for the success of an industrial concern.

Right from the very beginning, when the idea to set up an industrial unit generates in the mind of the entrepreneur, the initial investment is made in fixed assets, only then, enterprise will be in a position to work smoothly.

The amount of fixed capital required varies from business to business because of the following factors:

(1) Methods of handling production:

If a company is manufacturing all parts of a product, its fixed capital needs will be more, in comparison to an enterprise which is assembling parts produced by other concerns. For example, a bicycle factory which manufactures its own parts and then assembles them into a bicycle, needs huge amount of fixed capital. On the other hand, if a company assembles the parts manufactured by other firms, it will require small amount of fixed capital. Thus, the method of handling production also affects the magnitude of fixed capital.

(2) Mode of acquiring fixed assets:

Fixed assets can be either purchased or acquired on lease basis or taken on rent. In the first case, the requirement of fixed capital will be very high.

(3) Diversity of manufacturing lines:

If a company manufactures and markets its goods itself, it needs more fixed capital than a company engaged only in manufacturing a product. A trading concern buying and selling the goods produced by others will need very little fixed capital. Thus diversity of production lines also determines the fixed capital requirements.

(4) Nature of industry business:

The business enterprises engaged in rendering personal services, merchandise, commerce and trade may need very little fixed investment, while industries manufacturing heavy and capital goods are likely to invest a major part of their funds in fixed assets.

Similarly, a public utility undertaking (say, an electricity supply company, water supply undertaking or a railway company) would need heavy investment in fixed assets and equipment. Thus the nature of business determines the amount of fixed capital to a large extent.

(5) Kinds of products:

If the company is engaged in the manufacture of complicated goods like refrigerators, T.V. sets, motor vehicles, engines etc., it may need large amount of fixed capital than a business enterprise which produces simple consumer items like powder, cream, toothpaste etc. Thus the type of product manufactured also governs the amount of fixed capital.

(6) Size of the business unit:

A large scale firm requires more fixed capital than a small enterprise. The bigger the size of plant, the larger would be the amount of fixed investment. For instance, capital-intensive companies require huge amount to be invested in fixed assets as compared to labour-intensive companies.

Introduction to ownership Securities, Ordinary Shares, Reference Shares

Issue of share is the best method for the procurement of fixed capital requirements because it has not to be paid back to shareholder within the life time of the company. Funds raised through the issue of shares provide a financial floor to the capital structure of a company.

A share may be defined as a unit of measure of a shareholder’s interest in the company. “A share is a right to participate in the profits made by a company while it is a going concern and in the assets of the company when it is wound up.” (Bachan Cozdar Vs. Commissioner of Income tax). The share capital of company is divided into a large number of equal parts and each part is individually called a share.

Under the provisions of Section 86 of the Indian Companies Act, 1956, a public company or a private company which is subsidiary of a public company can issue only two types of shares i.e. equity shares and preference-shares. However, an independent private company can issue deferred shares as well.

Preference Shares:

Preference Shares are those shares which carry priority rights with regard to payment of dividend and return of capital.

According to Sec. 85 of the Indian Companies Act, preference share is that part of the share capital of the company which is endowed with the following preferential rights:

(1) Preference with regard to the payment of dividend at fixed rate; and

(2) Preference as to repayment of capital in the event of company being wound up.

Thus, Preference shareholders enjoy two preferential rights over the equity shares. Firstly, they are entitled to receive a fixed rate of dividend out of the net profits of the company prior to the declaration of dividend on equity shares.

Secondly, the assets remaining after the payment of debts of the company under liquidation are first distributed for returning preferential capital (contributed by the preference shareholders).

Types of Preference Shares:

(i) Cumulative and non-cumulative preference shares:

The holders of cumulative preference shares are sure to receive dividend on the preference shares held by them for all the years out of the earnings of the company. Under this the amount of unpaid dividend is carried forward as arrears and becomes the charge on the profits of the company.

If in any particular year they are not paid dividend, they will be paid such arrear in the next year before any dividend can be distributed among the equity shareholders. But the non-cumulative preference shareholders are entitled to their yearly dividend only if there is sufficient net profit in that year. In case the earnings are not adequate, dividends are not paid and the unpaid dividend is not carried forward for payment out of profits in subsequent years.

(ii) Participating and non-participating preference shares:

The holders of these preference shares are entitled to fixed rate of dividend and in addition they are also granted the right to share the surplus net profits of the company, left after paying a certain rate of dividend on equity shares. Thus, participating shareholders obtain return on their investments in two forms (a) fixed dividend (b) share in surplus profits.

The preference shares which do not carry the right to share in the surplus profits are known as non-participating preference shares.

(iii) Redeemable and irredeemable preference shares:

Redeemable preference shares are those which, in accordance with the terms of issue, can be redeemed or repaid after a certain date or at the discretion of the company. The preference shares which cannot be redeemed during the life time of the company are known as irredeemable preference shares.

(iv) Convertible and non-convertible preference shares:

If the preference shareholders are given the option to convert their shares into equity shares within a fixed period of time such shares will be known as convertible preference shares. The preference shares which cannot be converted into equity shares are called non- convertible preference shares.

(v) Guaranteed Preference Shares:

In case of conversion of a private concern into a limited company or in case of amalgamation and absorption the seller guarantees a particular rate of dividend on preference shares for certain years. These shares are called guaranteed preference shares.

Advantages of preference shares:

(1) Suitable to Cautious Investors. Preference shares mobilise the funds from such investors who prefer safety of their capital and want to earn income with greater certainty.

(2) Retention of Control. Control of the company is vested with the management by issuing preference shares to outsiders because such share-holders have restricted voting rights.

(3) Increase in the Income of Equity Shareholders. Preference shares bear a fixed yield and enable the company to adopt the policy of “trading on equity” to increase the rate of dividend on equities out of profits remaining after paying fixed rate of dividend on preference shares.

(4) Flexibility in the Capital Structure. In case of redeemable preference shares, company may feel at ease to bring flexibility in the financial structure as they can be redeemed whenever a company desires.

(5) No charge on Assets of the Company. The company can raise capital in the form of preference shares for a long term without creating any charge on its assets.

Disadvantages of preference shares:

(1) Permanent Burden:

Preference Shares Impose permanent burden on the company to pay fixed dividend prior to its disbursement among other types of shareholders.

(2) No Voting Right:

The preference shares may not be advantageous from the point of view of investors because they do not carry voting rights.

(3) Redemption during the period of Depression:

Preference shareholders will suffer the loss, if the company exercises its discretion to redeem the debentures during the periods of depression.

(4) Costly:

Compared to debentures and Govt., securities, the cost of raising the preference share capital is higher.

(5) Income Tax:

Since preference dividend is not an admissible deduction for income tax purposes, the company has to earn more, otherwise the dividend on equity shareholders will be affected.

Ordinary Shares/Equity Shares:

Equity shares or ordinary shares are those ownership securities which do not carry any special right in respect of annual dividend or the return of capital in the event of winding up of the company.

According to Sec. 85(2) of the Indian Companies Act.

“Equity shares (with reference to any company limited by shares) are those which are not preference shares”. A substantial part of risk capital of a company is raised from this source, which is of permanent nature.

Equity shareholders are the real owners of the company. They get dividend only after the dividend on preference shares is paid out of the profits of the company. They may not receive any return, if there are no profits. At the time of winding up of the company equity capital can be paid back after every claim including that of preference shareholders has been settled.

According to Hoagland, ‘ ‘Equity shareholders are the residual claimants against the assets and income of the corporation.”The financial risk is more with equity share capital. So equity shares are also called “Risk Capital.”

As the equity shareholders have higher risk, they also have a chance of getting higher dividend if the company earns higher profits. Equity shareholders control the affairs of the company because by possessing the voting rights they elect the directors of the company.

Advantages of Equity Shares:

(1) No Charge on Assets:

The company can raise the fixed capital without creating any charge over the assets.

(2) No-Recurring Fixed Payments:

Equity shares do not create any obligation on the part of company to pay fixed rate of dividend.

(3) Long term Funds:

Equity capital constitutes the permanent source of finance and there is no obligation for the company to return the capital except when the company is liquidated.

(4) Right to Participate in Affairs:

Equity shareholders, being the real owners of the company, have the right to participate in the affairs of the company.

(5) Appreciation in the value of Assets:

Investors in equity shares are rewarded by handsome dividends and appreciation in the value of their shareholdings under boom conditions.

(6) Ownership:

Equity shareholders are the real owners of the company. They alone have voting rights. They elect the directors to manage the company.

Disadvantages of Equity Shares:

(1) Difficulty in Trading on Equity:

The company will not be in a position to adopt the policy of trading on equity if all or most of the capital is raised in the form of equity shares.

(2) Speculation:

During the period of boom, higher dividends on equity shares results in the appreciation of the value of shares which in turn leads to speculation.

(3) Manipulation:

As the affairs of the company are controlled by equity shareholders on the basis of voting rights, there are chances of manipulation by a powerful group.

(4) Concentration of Control:

Whenever the company intends to raise capital by new issues, priority is to be given to existing shareholders. This may lead to concentration of power in few hands.

(5) Less Liquid:

Since equity shares are not refundable they are treated as illiquid.

(6) Not always Acceptable:

Because of the uncertainty of the return on the equity shares, conservative investors will hesitate to purchase them.

Deferred Shares:

The shares which are issued to the founders or promoters are called deferred shares or founders shares. The promoters take these shares for enabling them to control the company. These shares have extra ordinary rights though their face value is very low.

The holders of deferred shares can get dividend only after preference and equity shareholders shall have received their dividend.

Now-a-days, these shares have lost their popularity. At present in India public companies cannot issue deferred shares.

Creditorship Securities, Debtors and Bonds

A company can raise finances by issuing debentures. A debenture may be defined as the acknowledgement of debt by a company. Debentures constitute the borrowed capital of the company and they are known as creditorship securities because debenture holders are regarded as the creditors of the company. The debenture holders are entitled to periodical payment of interest at a fixed rate and are also entitled to redemption of their debentures as per the terms and conditions of the issue.

The word debenture is derived from the Latin word ‘Lebere’ meaning ‘to owe’. In its simplest sense it means a document which either creates or acknowledges a debt.

A debenture may be defined broadly, as “an instrument in writing, issued by a company under its seal and acknowledging a debt for a certain sum of money and giving an undertaking to repay that sum on or after a fixed future date and meanwhile to pay interest thereon at a certain rate per annum of stated Intervals.”

As per Sec. 2 (12) “debenture includes debenture stock, bonds and other securities of a company whether constituting a charge on the assets of the company or not.”

In the words of Chitty J. “Debenture means a document which either creates a debt acknowledges it, and any document which fulfills either of these conditions is a debenture.”

Palmer defines a debenture as “any instrument under seal of the company, evidencing a deed the essence of it being admission of indebtedness”. According to Evelyn Thomas “Debenture is a document under the company’s seal which provides for the payment of the principal sum and interest there on at regular intervals which is usually secured by a fixed or floating charge on the company’s property or undertaking and which acknowledges a company.”

On the analysis of above definitions, a debenture may be defined as an instrument executed by company under its common seal acknowledging indebtedness to some person or persons to secure the sum advanced. Debentures are usually bonds issued by the company in series of a fixed denomination e.g., Rs. 100, Rs. 200, Rs. 500, Rs. 1,000 of face value and are offered to the public by means of a prospectus.

The terms and conditions of ‘debenture issue’ are endorsed on the back of debenture certificate which gives different rights to the holders.

A company may have a debenture stock which is nothing but borrowed money consolidated into one mass for the sake of convenience. Instead of each lender having a separate bond or mortgage, he has a certificate entitling him to a certain sum, being a portion of one large loan.

Debentures or Bonds:

A company may raise long-term finance through public borrowings. These loans are raised by the issue of debentures. A debenture is an acknowledgement of a debt. According to Thomas Evelyn.

“A debenture is a document under the company’s seal which provides for the payment of a principal sum and interest thereon at regular intervals, which is usually secured by a fixed or floating charge on the company’s property or undertaking and which acknowledges a loan to the company’s property or undertaking and which acknowledges a loan to the company”.

A debenture-holder is a creditor of the company. A fixed rate of interest is paid on debentures. The interest on debentures is a charge on the profit and loss account of the company. The debentures are generally given a floating charge over the assets of the company. When the debentures are secured, they are paid on priority in comparison to all other creditors.

Convertible Debentures

The Convertible Debentures are a type of loan that can be converted into the stock of the company after a stipulated time period at the option of the holder or the issuer in special circumstances. These are issued with the intent to raise money to expand or maintain the business operations at a considerable low-interest rate.

The debentures are the long-term debt instruments on which the company is obliged to pay interest to its holders. Sometimes, the debentures are issued with an option of convertibility in which the debenture holder can get his debentures converted into the stock of the company, either fully or partly.

As per the SEBI, the following provisions apply in case the debentures are converted into the stock either fully or partly:

  1. The conversion time along with the conversion premium should be stated in the prospectus.
  2. The conversion, partial or full, must be at the disposal of the debenture holder, provided the conversion takes place at or after 18 months but before 36 months.
  3. The conversion is to be made optional with “put” or “call” option in case the debentures provide for conversion after 36 months.
  4. In case, the conversion period of fully convertible debentures exceeds 18 months; then a compulsory credit rating is required.

Through above provisions, it is clear that the convertible debentures could be of three types:

  1. Compulsory convertible debentures provide for the conversion within 18 months of the issue
  2. Optional convertible debentures provide for the conversion within 36 months of the issue.
  3. Debenture with “call “or “put” option in case the conversion exceeds 36 months.

The convertible debentures are beneficial to the investor since they get an opportunity to become the owner of the company and might leave in case the company experiences the loss. But however, the convertible debentures are unsecured and in case the company goes bankrupt, the holder gets his money only after all the secured creditors are paid.

The major disadvantage to the issuer is that, if the company makes huge profits, then the investor would like to become the shareholder or the owner which results in the dilution of ownership in the company.

Types of Convertible Debentures

Fully Convertible Debentures

Under these securities, the whole value of debentures is convertible into equity shares of the company. The ratio of conversion is determined at the time of issue of these securities.

Partly Convertible Debentures

These securities differ from fully convertible ones. Under them, only some part of the debentures is eligible for conversion into equity shares. Again, the ratio of conversion is determined at the time of issuance of these securities. A part of the debt can be converted into equity shares after the approval of debt holders.

Concept of Private Placement of Securities

A private placement is a capital raising event that involves the sale of securities to a relatively small number of select investors.

A private placement is different from a public issue in which securities are made available for sale on the open market to any type of investor.

As per the definition under Explanation II to Sub Section 1 of Section 42 of the Companies Act, 2013 Private Placement means any offer of securities or invitation to subscribe securities to a select group of persons by a Company ( other than by way of public offer) through issue of a private placement offer letter and which satisfies the conditions specified in this section.

Private Placement is governed by Section 42 of the Companies Act, 2013. As per Section 42 of the Companies Act, 2013 the maximum number of persons to which allotment can be done in a year shall not exceed 200( Excluding Qualified Institutional Buyers and Employees who have been given securities under ESOP Scheme) in a financial year. If the same exceeds the prescribed limit then in will be deemed to be a public issue and the Company has to follow the procedure of Public issue. As per the present scenario, if a Company, listed or unlisted, makes an offer of Securities to more than 200 persons during a year, whether it receives money or not, to any person whether in India or abroad and intends to get its Securities listed on a recognized stock exchange whether in India or abroad, shall be deemed to be a Public issue and the Company has to Comply with the provisions of Public issue.

Procedure

  1. Company planning to make Private Placement has to first pass a special resolution in the general meeting of the Company.

However, in case of Non Convertible Debentures(NCD) it will be sufficient if the Company passes a special resolution once in a year for all the Private Placements to be made by the for the NCD during the year.[Rule 14(2)].

  1. Next, the Company has to issue a Private Placement letter of offer to the Identified persons by the Board to whom the allotment is to be made. [ Companies Amendment Act, 2017].

However, it is to be noted that the Private Placement letter of offer shall not contain Right to Renunciation.[ Companies Amendment Act, 2017].

The Company also has to keep the records of the same and file the details with the ROC within 30 days from the date of issue of Private Placement letter of offer.[Rule 14(3)].

  1. Once the Company receives the allotment money, the Company shall allot the Securities within 60 days and if it fails to do so then refund the money within the next 15 days. If the Company fails to do so then interest @12% will be charged from the expiry of 60th day.
  2. The Company has to file return of allotment within 15 days of allotment in Form PAS-3 .Companycannot utilize the Application money until it has filed Return of allotment with the ROC[ Companies Amendment Act, 2017].

Following points are to be noted

  1. The Application money to be received shall be either through Cheque, Demand Draft or other banking channels except cash. [Section 42(5)]
  2. The minimum application size shall not be less than Rupees Twenty Thousand per person.
  3. Private Placement shall not be done unless any previous offer or invitation has been completed or withdrawn or abandoned by the Company. [Section 42(3)].
  4. The Company shall not advertise about the Private Placement to the public.
  5. If a Company makes contravenes the provisions of this Section, then the Company, Promoters and its Directors shall be liable for a penalty which may extend to the amount involved in the contravention or rupees two crores, whichever is higher. Further the Company also has to refund all monies to subscribers within 30 days of the order.
  6. Restriction of 200 is for each kind of a Security .

Private Placement Advantages

Private placements present the following advantages:

  • Long Term
    Private placements provide longer maturities than typical bank financing, at a fixed-interest rate. This is ideal for when a business is presented with a growth opportunity where they wouldn’t see the return on their investment right away; a business would have more time to pay back the private placement while having certainty of financing cost over the life of that investment.
    Also, private placements are typically “buy-and-hold,” so the company would benefit from having a long-term relationship with the same investor throughout the life of the financing.
  • Speed in Execution
    The growth and maturity of the private placement market has led to improved standardization of documentation, visibility of pricing and terms, increased capacity for financings as well as overall increase of size and depth of the market ($10MM – $1B+). Thus, the private placement market fosters an environment that allows for quick execution of an investment, generally within 6-8 weeks (for the first transaction. Follow-on financings can be executed within a shorter time frame).

    Additionally, it is typically faster to issue a private placement versus a corporate bond in the public market because the issuer is not required to expend time and resources creating a prospectus and registering with the SEC.
  • Complement to Existing Financing
    Private placements also help diversify a company’s sources of capital and capital structure. Since the terms can be customized, private placements can complement existing bank debt versus compete with it, and can allow a company to better manage its debt obligations. Diversification of funding sources is particularly important during market cycles when bank liquidity may be tight.

    Private placements enable privately-held, middle-market companies and public companies to access capital just as they would with an underwritten public debt offering, but without certain requirements, such as ratings, registrations, or minimum size. And for public companies, private placements can offer superior execution relative to the public bond market for small issuance sizes as well as greater structural flexibility.
  • Privacy and Control
    Private placement transactions are negotiated confidentially. Also, public disclosure requirements are limited, compared to those found in the public market. Companies would not be beholden to public shareholders.

Uses

Long-term capital is congruent with a company’s long-term investments. Thus, capital raised from issuing a private placement is most commonly used to support long-term initiatives versus short-term needs, such as working capital. Companies, both public and private, use the capital raised from private placements in the following ways:

  • Debt refinancing
  • Debt diversification
  • Expansion/Growth capital
  • Acquisitions
  • Stock buyback/Recapitalization
  • Taking a public company privat
  • Employee Stock Ownership Plan (ESOP)

Pricing and Payment Structure

Private placement debt is predominantly a fixed-income note that pays a set coupon, on a negotiated schedule. Private placements are priced similarly to public securities, where pricing is determined by the U.S. Treasury rate, with the addition of a credit risk premium.

Repayment of the principal can be accomplished in several ways, depending on the credit quality and needs of the issuer, such as sinking fund payments (amortization) or “bullets” as well as tailored/bespoke amortization. Interest is typically paid quarterly or semi-annually.

Working capital funds

Working Capital is basically an indicator of the short-term financial position of an organization and is also a measure of its overall efficiency. Working Capital is obtained by subtracting the current liabilities from the current assets. This ratio indicates whether the company possesses sufficient assets to cover its short-term debt.

Working Capital indicates the liquidity levels of companies for managing day-to-day expenses and covers inventory, cash, accounts payable, accounts receivable and short-term debt that is due. Working capital is derived from several company operations such as debt and inventory management, supplier payments and collection of revenues.

The sources for working capital can either be long term, short term or even spontaneous. Spontaneous working capital are majorly derived from trade credit including notes payable and bills payable while short term working capital sources include dividend or tax provisions, cash credit, public deposits, trade deposits, short-term loans, bills discounting, inter-corporate loans and also commercial paper.

For the long-term, working capital sources include long-term loans, provision for depreciation, retained profits, debentures and share capital. These are major working capital sources for organizations based on their requirements.

Types of Working Capital

There are several types of working capital based on the balance sheet or operating cycle view. The balance sheet view classifies working capital into net (current liabilities subtracted from current assets featuring in the company’s balance sheet) and gross working capital (current assets in the balance sheet).

On the other hand, operating cycle view classifies working capital into temporary (difference between net working capital & permanent working capital) and permanent (fixed assets) working capital. Temporary working capital can be further broken down into reserve.

Working Capital Cycle

The Working Capital Cycle or WCC means the time period that is taken to convert net current liabilities and assets into cash by any organization. This is an indicator of the organizational efficiency in terms of effectively managing liquidity position in the short-term and the cycle, which is calculated in days, is basically the time period between the generation of revenue through cash by selling products and the buying of materials for producing these products.

The shorter this working capital cycle, the swifter will the company be able to free up its cash, which is blocked. In case the cycle is long, the capital usually gets stuck without earning returns in the operational cycle. Businesses always strive to lower this working capital cycle with a view towards enhancing liquidity in the short-term.

Working Capital Formula

The formula for working capital is the following:

Working Capital = Current Assets – Current Liabilities

The working capital ratio is the indicator of whether ample short-term assets are possessed by an organization for taking care of short-term debt. A ratio lower than 1 is an indicator of negative working capital while positive/sufficient working capital is usually indicated by a ratio between 1.2 and 2.0. Anything exceeding 2 usually indicates there are excess assets that are not being invested by the company and therefore represents missed opportunity.

The organization may be in trouble if the current assets do not exceed the liabilities at present. Working capital also provides a picture of the efficiency of the organization. Money that is locked in the market, inventory or in the hands of customers-who have not paid up yet, will not be considered viable when it comes to settling obligations.

Funding Working Capital

  • Zero collateral requirements
  • Loans up to Rs. Crore within 24 hours
  • Flexi Interest-only Loans where EMIs could consist of only interest, with principal payable at the end of the tenor
  • Doorstep document pick-up for faster processing
  • Swift online application & approval process
  • Minimal Documentation: Only KYC documents, business vintage, passport-sized photo and financial documents are required.
  • Easy-to-meet eligibility criteria for SMEs and business-owners

Introduction to Capital Structure Theories

Capital Structure means a combination of all long-term sources of finance. It includes Equity Share Capital, Reserves and Surplus, Preference Share capital, Loan, Debentures and other such long-term sources of finance. A company has to decide the proportion in which it should have its own finance and outsider’s finance particularly debt finance. Based on the proportion of finance, WACC and Value of a firm are affected. There are four capital structure theories for this, viz. net income, net operating income, traditional and M&M approach.

Net income

Net income approach and net operating income approach were proposed by David Durand. According to NI approach, there exists positive relationship between capital structure and valuation of firm and change in the pattern of capitalisation brings about corresponding change in the overall cost of capital and total value of the firm.

Thus, with an increase in the ratio of debt to equity overall cost of capital will decline and market price of equity stock as well as value of the firm will rise. The converse will hold true if ratio of debt to equity tends to decline.

This approach is based on three following assumptions:

(1) There are no taxes;

(2) Cost of debt is less than cost of equity;

(3) The use of debt does not change the risk perception of investors. This implies that there will be no change in cost of debt and cost of equity even if degree of financial leverages changes.

On the basis of the above assumptions, it has been held in the NI approach that increased use of debt will magnify the shareholders’ earnings (because cost of debt and cost of equity will remain constant) and thereby result in rise in share values of equity and so also value of the firm.

Thus, a firm can achieve optimal capital structure by making judicious use of debt and equity and attempt to maximise the market price of its stock.

According to NI approach a firm may increase the total value of the firm by lowering its cost of capital.

When cost of capital is lowest and the value of the firm is greatest, we call it the optimum capital structure for the firm and, at this point, the market price per share is maximised.

The same is possible continuously by lowering its cost of capital by the use of debt capital. In other words, using more debt capital with a corresponding reduction in cost of capital, the value of the firm will increase.

The same is possible only when:

(i) Cost of Debt (Kd) is less than Cost of Equity (Ke);

(ii) There are no taxes; and

(iii) The use of debt does not change the risk perception of the investors since the degree of leverage is increased to that extent.

Since the amount of debt in the capital structure increases, weighted average cost of capital decreases which leads to increase the total value of the firm. So, the increased amount of debt with constant amount of cost of equity and cost of debt will highlight the earnings of the shareholders.

Net Operating Income Approach (NOI):

According to Net Operating Income Approach which is just opposite to NI approach, the overall cost of capital and value of firm are independent of capital structure decision and change in degree of financial leverage does not bring about any change in value of firm and cost of capital.

The market value of the firm is determined by the following formula:

The crucial assumptions of the NOI approach are:

(1) The firm is evaluated as a whole by the market. Accordingly, overall capitalisation rate is used to calculate the value of the firm. The split of capitalisation between debt and equity is not significant.

(2) Overall capitalisation rate remains constant regardless of any change in degree of financial leverage.

(3) Use of debt as cheaper source of funds would increase the financial risk to shareholders who demand higher cost on their funds to compensate for the additional risk. Thus, the benefits of lower cost of debt are offset by the higher cost of equity.

(4) The cost of debt would stay constant.

(5) The firm does not pay income taxes.

Thus, under the NOI approach the total value of the firm as stated above is determined by dividing the net operating income (EBIT) by the overall capitalisation rate and market value of equity (S) can be found out by subtracting the market value of debt (B) from the overall value of the firm (V). In other words.

Now we want to highlight the Net Operating Income (NOI) Approach which was advocated by David Durand based on certain assumptions.

They are:

(i) The overall capitalisation rate of the firm Kw is constant for all degree of leverages;

(ii) Net operating income is capitalised at an overall capitalisation rate in order to have the total market value of the firm.

Thus, the value of the firm, V, is ascertained at overall cost of capital (Kw):

V = EBIT/Kw (since both are constant and independent of leverage)

(iii) The market value of the debt is then subtracted from the total market value in order to get the market value of equity.

S – V – T 

(iv) As the Cost of Debt is constant, the cost of equity will be

Ke = EBIT – I/S

The NOI Approach can be illustrated with the help of the following diagram

Under this approach, the most significant assumption is that the Kw is constant irrespective of the degree of leverage. The segregation of debt and equity is not important here and the market capitalises the value of the firm as a whole.

Thus, an increase in the use of apparently cheaper debt funds is offset exactly by the corresponding increase in the equity- capitalisation rate. So, the weighted average Cost of Capital Kw and Kd remain unchanged for all degrees of leverage. Needless to mention here that, as the firm increases its degree of leverage, it becomes more risky proposition and investors are to make some sacrifice by having a low P/E ratio.

Traditional Approach:

While the above two approaches represent extreme views about the impact of financial leverage on value of firm and cost of capital, traditional approach offers an intermediate view which is a compromise between the NOI and NI approaches.

This approach resembles the NI approach when it argues that the value of the firm can be increased and cost of capital can be reduced by the judicious mix of debt and equity share capital but it does not subscribe to the view of NI approach that the value of the firm will increase and cost of capital will decrease for all the degrees of financial leverage.

Further, the traditional approach differs from the NOI approach because it does not hold the view that the overall cost of capital will remain constant whatever be the degree of financial leverage. Traditional theorists believe that up to certain point a firm can by increasing proportion of debt in its capital structure reduce cost of capital and raise market value of the stock.

Beyond the point further induction of debt will lead the cost of capital to rise and market value of the stock to fall. Thus, through a judicious mix of debt and equity a firm can minimise overall cost of capital to maximise value of stock. They opine that optimal point in capital structure is one where overall cost of capital begins to rise faster than the increase in earnings per share as a result of application of additional debt.

Traditional view regarding optimal capital structure can be appreciated by categorizing the market reaction to leverage in following three stages:

Stage I:

The first stage starts with introduction of debt in the firm’s capital structure. As a result of the use of low cost debt the firm’s net income tends to rise; cost of equity capital (Ke) rises with addition of debt but the rate of increase will be less than the increase in net earnings rate. Cost of debt (Ki,) remains constant or rises only modestly. Combined effect of all these will be reflected in increase in market value of the firm and decline in overall cost of capital (K0).

Stage II:

In the second stage further application of debt will raise costs of debt and equity capital so sharply as to offset the gains in net income. Hence the total market value of the firm would remain unchanged.

Stage III:

After a critical turning point any further dose of debt to capital structure will prove fatal. The costs of both debt and equity rise as a result of the increasing riskiness of each resulting in an increase in overall cost of capital which will be faster than the rise in earnings from the introduction of additional debt. As a consequence of this market value of the firm will tend to depress.

The overall effect of these stages suggests that the capital structure decision has relevance to valuation of firm and cost of capital. Up to favorably affects the value of a firm. Beyond that point value of the firm will be adversely affected by use of debt. 

The traditional view of optimal structure is set forth graphically in figure 14.3.

It may be noted from figure 14.3 that the cost of capital curve (Ke) is saucer shaped where an optimal range is extended over the range of leverage. But cost of capital curve need not always be saucer shaped. It is possible that stage 2 may not exist at all and instead of optimal range we may have optimal point in capital structure. This possibility is shown in figure 14.4.

Thus, cost of capital curve may be V shaped which yudecdes that applications of additional debt in capital structure beyond a point will result in an increase in total cost of capital and fall in market value of the firm. This is an optimal level of debt and equity mix which every firm must endeavour to attain.

Modigliani-Miller (M-M) Approach:

Modigliani-Miller’ (MM) advocated that the relationship between the cost of capital, capital structure and the valuation of the firm should be explained by NOI (Net Operating Income Approach) by making an attack on the Traditional Approach.

The Net Operating Income Approach, supplies proper justification for the irrelevance of the capital structure. In Income Approach, supplies proper justification for the irrelevance of the capital structure.

In this context, MM support the NOI approach on the principle that the cost of capital is not dependent on the degree of leverage irrespective of the debt-equity mix. In the words, according to their thesis, the total market value of the firm and the cost of capital are independent of the capital structure.

They advocated that the weighted average cost of capital does not make any change with a proportionate change in debt-equity mix in the total capital structure of the firm.

The same can be shown with the help of the following diagram

Proposition:

The following propositions outline the MM argument about the relationship between cost of capital, capital structure and the total value of the firm:

(i) The cost of capital and the total market value of the firm are independent of its capital structure. The cost of capital is equal to the capitalisation rate of equity stream of operating earnings for its class, and the market is determined by capitalising its expected return at an appropriate rate of discount for its risk class.

(ii) The second proposition includes that the expected yield on a share is equal to the appropriate capitalisation rate of a pure equity stream for that class, together with a premium for financial risk equal to the difference between the pure-equity capitalisation rate (Ke) and yield on debt (Kd). In short, increased Ke is offset exactly by the use of cheaper debt.

(iii) The cut-off point for investment is always the capitalisation rate which is completely independent and unaffected by the securities that are invested.

Assumptions:

The MM proposition is based on the following assumptions:

(a) Existence of Perfect Capital Market It includes:

(i) There is no transaction cost;

(ii) Flotation costs are neglected;

(iii) No investor can affect the market price of shares;

(iv) Information is available to all without cost;

(v) Investors are free to purchase and sale securities.

(b) Homogeneous Risk Class/Equivalent Risk Class:

It means that the expected yield/return have the identical risk factor i.e., business risk is equal among all firms having equivalent operational condition.

(c) Homogeneous Expectation:

All the investors should have identical estimate about the future rate of earnings of each firm.

(d) The Dividend pay-out Ratio is 100%:

It means that the firm must distribute all its earnings in the form of dividend among the shareholders/investors, and

(e) Taxes do not exist:

That is, there will be no corporate tax effect (although this was removed at a subsequent date).

Interpretation of MM Hypothesis:

The MM Hypothesis reveals that if more debt is included in the capital structure of a firm, the same will not increase its value as the benefits of cheaper debt capital are exactly set-off by the corresponding increase in the cost of equity, although debt capital is less expensive than the equity capital. So, according to MM, the total value of a firm is absolutely unaffected by the capital structure (debt-equity mix) when corporate tax is ignored.

Proof of MM Hypothesis: The Arbitrage Mechanism:

MM have suggested an arbitrage mechanism in order to prove their argument. They argued that if two firms differ only in two points viz. (i) the process of financing, and (ii) their total market value, the shareholders/investors will dispose-off share of the over-valued firm and will purchase the share of under-valued firms.

Naturally, this process will be going on till both attain the same market value. As such, as soon as the firms will reach the identical position, the average cost of capital and the value of the firm will be equal. So, total value of the firm (V) and Average Cost of Capital, (Kw) are independent.

EBIT-EPS analysis for Capital Structure Decision

EBIT-EPS Analysis is a financial tool used to determine the impact of different financing options (debt and equity) on a company’s Earnings Per Share (EPS) at various levels of Earnings Before Interest and Taxes (EBIT). It helps in capital structure decision-making, allowing firms to choose between debt financing (which increases financial leverage) and equity financing (which avoids fixed interest costs but dilutes ownership). The analysis involves computing EPS for different EBIT levels to identify the indifference point, where EPS remains the same regardless of financing choice. Companies aim to maximize EPS while managing financial risk and shareholder value.

Meaning of EBIT

Earnings Before Interest and Taxes (EBIT) refers to the operating profit of the firm.
It is the income earned from business operations before deducting interest on loans and income tax.

EBIT = OperatingRevenue – OperatingExpenses

It measures the earning capacity of the firm independent of financing decisions.

Meaning of EPS

Earnings Per Share (EPS) represents the earnings available to each equity shareholder.
It indicates the profitability of the company from the shareholders’ point of view.

EPS = Earnings available to equity shareholders / Number of equity shares

Higher EPS means higher return to shareholders and increased market value of shares.

Financial Leverage and EBIT–EPS

The analysis is closely related to financial leverage.

Financial leverage means the use of debt in capital structure to increase return to equity shareholders.

  • If EBIT is high → Debt financing increases EPS

  • If EBIT is low → Debt financing decreases EPS

Therefore, proper use of debt can increase shareholders’ wealth.

Advantages of EBIT-EPS Analysis

  • Helps in Selecting Optimum Capital Structure

EBIT–EPS analysis helps management compare different financing alternatives such as equity shares, preference shares and debt. By calculating earnings per share under each plan, the company can identify the most profitable financing option. The plan that provides higher EPS at a particular level of EBIT is selected. Thus, it guides the finance manager in designing an optimum capital structure that balances cost and return while improving the financial performance of the organization.

  • Maximizes Shareholders’ Earnings

The main objective of financial management is to maximize the wealth of equity shareholders. EBIT–EPS analysis directly focuses on earnings available to shareholders. It shows how different financing plans affect EPS and helps management select the alternative that produces higher earnings per share. By choosing the plan with the highest EPS, the firm increases returns to shareholders, enhances investor confidence and improves the market value of shares.

  • Measures the Effect of Financial Leverage

EBIT–EPS analysis clearly explains the effect of financial leverage on shareholders’ earnings. It shows how the use of borrowed funds can increase EPS when operating profits are high. At the same time, it also reveals the negative impact when profits decline. Therefore, it helps management understand both benefits and dangers of debt financing. This knowledge assists in maintaining a proper balance between risk and return while planning the capital structure.

  • Useful in Financial Planning

The analysis is very helpful in financial planning and forecasting. It enables the company to estimate the level of operating profit required to meet interest and dividend obligations. Management can predict future earnings and evaluate the financial viability of proposed financing plans. This makes planning more systematic and reduces uncertainty in financial decision-making. As a result, the company can arrange funds in advance and avoid financial difficulties.

  • Facilitates Comparison of Financing Alternatives

A company often has several alternatives for raising funds, such as issuing shares or taking loans. EBIT–EPS analysis provides a numerical comparison of these alternatives. It presents the impact of each option on EPS in a clear and measurable form. This makes decision-making logical and objective rather than based on assumptions. Hence, management can select the most beneficial financing source after evaluating all possible alternatives.

  • Identifies the Indifference Point

EBIT–EPS analysis helps determine the indifference point, which is the level of EBIT where EPS remains the same under two financing plans. This point guides management in understanding the level of operating income required for debt financing to become advantageous. Above this level, debt financing is preferable, while below it equity financing is safer. Therefore, the indifference point provides a clear basis for selecting suitable financial strategies.

  • Improves Decision-Making

The technique promotes scientific and rational financial decision-making. Instead of relying on guesswork, management uses calculated figures of EPS to choose financing sources. It provides a clear picture of expected returns and financial obligations. This reduces uncertainty and improves confidence in financial decisions. Consequently, the organization can adopt policies that are more effective, practical and aligned with long-term business goals.

  • Assists in Profit Planning

EBIT–EPS analysis also helps in profit planning. By analyzing different EBIT levels, the firm can set profit targets required to achieve desired EPS. Management can evaluate whether expected operating profits are sufficient to cover fixed financial charges. This enables better budgeting and performance evaluation. Therefore, the analysis acts as a useful tool for planning profitability and monitoring the financial performance of the business.

Limitations of EBIT-EPS Analysis

Although EBIT–EPS analysis is a useful technique for selecting an appropriate financing plan and capital structure, it is not free from defects. The analysis mainly concentrates on earnings per share and ignores several practical aspects of financial decision-making. Therefore, it should not be used as the only basis for financing decisions.

The major limitations of EBIT–EPS analysis are explained below:

  • Ignores Business Risk

EBIT–EPS analysis assumes that the operating income (EBIT) is known and stable. In reality, business earnings fluctuate due to changes in demand, competition, economic conditions and technology. If EBIT decreases unexpectedly, the company may not be able to meet interest obligations on debt. Hence, the analysis does not properly consider business risk, which is an important factor in financial planning.

  • Focuses Only on EPS

The technique gives importance only to earnings per share. However, maximizing EPS does not always mean maximizing shareholders’ wealth. Shareholders are also concerned with share price, dividends, safety of investment and future growth. A plan with higher EPS may involve higher risk and may reduce the market value of shares. Therefore, EPS alone is not a complete measure of financial performance.

  • Neglects Financial Risk

EBIT–EPS analysis encourages the use of debt because it often increases EPS at higher levels of EBIT. However, excessive debt increases financial risk and the possibility of insolvency. The company must pay interest regardless of profit. The analysis does not give adequate weight to the risk arising from heavy borrowing, which may endanger the long-term stability of the firm.

  • Assumes Constant Interest and Tax Rates

The analysis assumes that interest rates and tax rates remain constant. In actual business conditions, interest rates change due to market fluctuations and government policies. Similarly, tax rates may also vary. Changes in these rates directly affect EPS and the cost of capital. Hence, results of the analysis may become unrealistic or misleading.

  • Ignores Market Conditions

EBIT–EPS analysis does not consider the condition of the capital market. Sometimes it may not be possible to issue shares or debentures due to unfavorable market situations. Investor preferences, economic recession and stock market trends also affect financing decisions. Since these practical aspects are ignored, the analysis may not always be applicable in real situations.

  • No Consideration of Control

Issue of equity shares reduces the ownership control of existing shareholders. Many companies avoid issuing new shares to maintain management control. EBIT–EPS analysis does not consider this important aspect. It only compares EPS and ignores the effect of financing decisions on voting rights and managerial control.

  • Unrealistic Assumption of Fixed EBIT Levels

The technique compares financing plans at different EBIT levels, but predicting exact EBIT in advance is difficult. Business profits are uncertain and affected by several external factors. If the actual EBIT differs from estimated EBIT, the selected financing plan may not be suitable. Therefore, the analysis may lead to wrong decisions when profit estimates are inaccurate.

  • Does Not Consider Cash Flow Position

EBIT–EPS analysis is based on accounting profits rather than cash flows. However, interest and loan repayments require actual cash payments. A firm may show high EPS but may still face cash shortage. Ignoring liquidity position may create financial difficulties and even bankruptcy.

  • Short-Term Perspective

The analysis mainly focuses on immediate effect on EPS and does not consider long-term consequences such as growth opportunities, financial flexibility and sustainability. A financing plan beneficial in the short run may harm the company in the long run. Therefore, it provides only a partial view of financial decision-making.

Indifference Points:

The indifference point, often called as a breakeven point, is highly important in financial planning because, at EBIT amounts in excess of the EBIT indifference level, the more heavily levered financ­ing plan will generate a higher EPS. On the other hand, at EBIT amounts below the EBIT indifference points the financing plan involving less leverage will generate a higher EPS.

Indifference points refer to the EBIT level at which the EPS is same for two alternative financial plans. According to J. C. Van Home, ‘Indifference point refers to that EBIT level at which EPS remains the same irrespective of debt equity mix’. The management is indifferent in choosing any of the alternative financial plans at this level because all the financial plans are equally desirable. The indifference point is the cut-off level of EBIT below which financial leverage is disadvanta­geous. Beyond the indifference point level of EBIT the benefit of financial leverage with respect to EPS starts operating.

The indifference level of EBIT is significant because the financial planner may decide to take the debt advantage if the expected EBIT crosses this level. Beyond this level of EBIT the firm will be able to magnify the effect of increase in EBIT on the EPS.

In other words, financial leverage will be favorable beyond the indifference level of EBIT and will lead to an increase in the EPS. If the expected EBIT is less than the indifference point then the financial planners will opt for equity for financing projects, because below this level, EPS will be more for less levered firm.

  • Computation

We have seen that indifference point refers to the level of EBIT at which EPS is the same for two different financial plans. So the level of that EBIT can easily be computed. There are two approaches to calculate indifference point: Mathematical approach and graphical approach.

  • Graphical Approach

The indifference point may also be obtained using a graphical approach. In Figure 5.1 we have measured EBIT along the horizontal axis and EPS along the vertical axis. Suppose we have two financial plans before us: Financing by equity only and financing by equity and debt. Dif­ferent combinations of EBIT and EPS may be plotted against each plan. Under Plan-I the EPS will be zero when EBIT is nil so it will start from the origin.

The curve depicting Plan I in Figure 5.1 starts from the origin. For Plan-II EBIT will have some positive figure equal to the amount of interest to make EPS zero. So the curve depicting Plan-II in Figure 5.1 will start from the positive intercept of X axis. The two lines intersect at point E where the level of EBIT and EPS both are same under both the financial plans. Point E is the indifference point. The value corresponding to X axis is EBIT and the value corresponding to 7 axis is EPS.

These can be found drawing two perpendiculars from the indifference point—one on X axis and the other on Taxis. Similarly we can obtain the indifference point between any two financial plans having various financing options. The area above the indifference point is the debt advantage zone and the area below the indifference point is equity advantage zone.

Above the indifference point the Plan-II is profitable, i.e. financial leverage is advantageous. Below the indifference point Plan I is advantageous, i.e. financial leverage is not profitable. This can be found by observing Figure 5.1. Above the indifference point EPS will be higher for same level of EBIT for Plan II. Below the indifference point EPS will be higher for same level of EBIT for Plan I. The graphical approach of indifference point gives a better understanding of EBIT-EPS analysis.

Financial Breakeven Point

In general, the term Breakeven Point (BEP) refers to the point where the total cost line and sales line intersect. It indicates the level of production and sales where there is no profit and no loss because here the contribution just equals to the fixed costs. Similarly financial breakeven point is the level of EBIT at which after paying interest, tax and preference dividend, nothing remains for the equity shareholders.

In other words, financial breakeven point refers to that level of EBIT at which the firm can satisfy all fixed financial charges. EBIT less than this level will result in negative EPS. Therefore EPS is zero at this level of EBIT. Thus financial breakeven point refers to the level of EBIT at which financial profit is nil.

Financial Break Even Point (FBEP) is expressed as ratio with the following equation:

Cost of Debt, Functions, Theories, Applications, Challenges

Cost of debt represents the effective rate a firm pays on its borrowed funds, including loans, bonds, and debentures, reflecting the return required by lenders for providing capital. Unlike cost of equity, cost of debt is generally more straightforward to determine, as it is often based on the contractual interest rate specified in borrowing agreements, adjusted for any associated issuance costs or premiums. Since interest payments are typically tax-deductible, firms usually calculate the after-tax cost of debt to reflect the actual cost borne after accounting for tax benefits, making debt a relatively cheaper source of financing compared to equity. Cost of debt plays a crucial role in determining a firm’s overall weighted average cost of capital and influences capital structure decisions significantly.

Functions of Cost of Debt:

1. Determinant of Weighted Average Cost of Capital

Cost of debt serves as a critical input in calculating a firm’s Weighted Average Cost of Capital, as it represents one of the primary components of the overall capital structure alongside cost of equity. Since debt is generally cheaper than equity due to its tax-deductible interest payments and lower risk to lenders, the proportion and cost of debt significantly influence the blended overall cost of capital used for investment appraisal. An accurate estimation of cost of debt ensures that the WACC reflects the true cost of financing, enabling firms to make sound decisions regarding project acceptance, rejection, and overall capital budgeting processes.

2. Basis for Capital Structure Decisions

Cost of debt plays a central role in guiding a firm’s capital structure decisions, as management compares the relative costs of debt and equity financing to determine the optimal mix that minimizes the overall cost of capital while balancing financial risk. A lower cost of debt, especially after accounting for tax shields, often makes borrowing an attractive financing option compared to equity, which carries no tax deductibility on returns paid to shareholders. However, firms must weigh this cost advantage against the increased financial risk and potential distress costs associated with higher leverage, making cost of debt a key factor in structuring the firm’s financing decisions.

3. Tool for Evaluating Financing Alternatives

Cost of debt enables firms to systematically compare different borrowing options, such as bank loans, debentures, bonds, or commercial paper, each carrying different interest rates, terms, and associated costs. By calculating and comparing the effective cost of each financing alternative, management can select the most cost-efficient source of debt capital for a given financing need. This function is particularly important when firms have access to multiple funding sources with varying risk profiles, maturities, and covenants, as understanding the true cost of each option allows for more informed and financially sound borrowing decisions across different market conditions.

4. Influences Investment Appraisal and Project Selection

Cost of debt directly affects the discount rate used in evaluating projects financed partly or wholly through borrowed funds, influencing key investment appraisal metrics such as net present value and internal rate of return. Since debt-financed projects must generate returns sufficient to cover the cost of servicing that debt, an accurate cost of debt calculation ensures that project evaluation reflects the true financial burden of the chosen financing method. This function helps firms avoid accepting projects that fail to generate adequate returns to justify the cost of the debt capital used to fund them, protecting long-term financial stability.

5. Reflects Firm’s Credit Risk and Market Perception

The cost of debt a firm faces serves as an indicator of how lenders and credit markets perceive its overall creditworthiness and financial risk, with higher costs signaling greater perceived risk of default. Firms with strong credit ratings and stable cash flows typically secure debt at lower interest rates, while those with weaker financial positions face higher borrowing costs. This function makes cost of debt a useful external signal, allowing management, investors, and analysts to gauge market confidence in the firm’s financial health and stability based on the terms at which the firm is able to raise debt capital.

Theories of Cost of Debt:

1. Yield to Maturity Theory

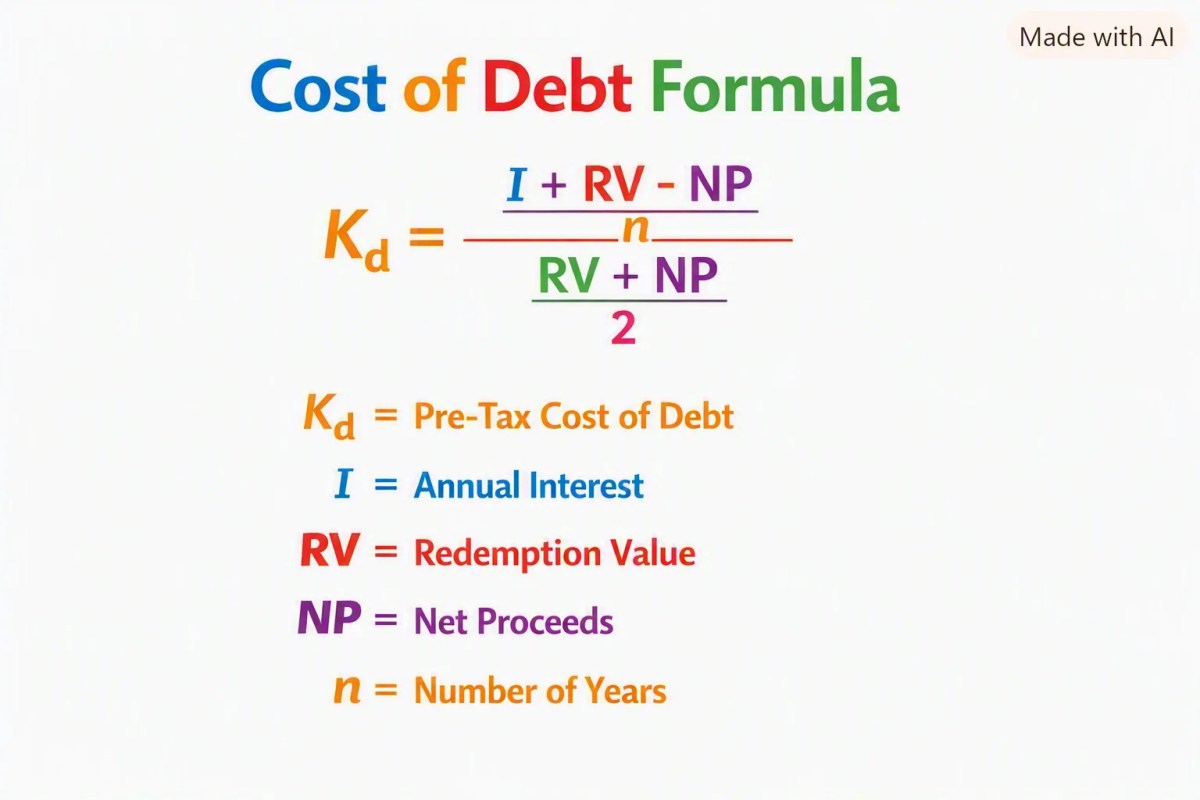
The Yield to Maturity approach estimates the cost of debt by considering the return required by lenders on a debt instrument until its maturity. It considers the current market price of the debt, annual interest payments, redemption value and remaining maturity period. This approach provides a market based estimate of the borrowing cost, particularly for market traded bonds and debentures. When the debt is issued at a discount or premium, the effective cost may differ from the stated interest rate. Therefore, Yield to Maturity provides a comprehensive measure of the actual pre tax cost of debt.

2. Net Proceeds Approach

The Net Proceeds Approach calculates the cost of debt by comparing the annual interest and repayment obligations with the actual amount of funds received by the company. It is particularly useful when debt is issued at a discount or when flotation and issue expenses are involved. The approach provides an effective borrowing cost rather than simply considering the stated interest rate. If issue expenses or discounts reduce the amount received, the effective cost of borrowing increases. Therefore, this approach helps management evaluate the actual cost associated with raising debt finance.
3. Present Value Approach

The Present Value Approach determines the cost of debt by finding the discount rate that equates the present value of future debt cash outflows with the net proceeds received by the company. Future interest payments and redemption amounts are discounted at the rate representing the effective cost of debt. This approach is more accurate because it considers the timing and amount of all relevant cash flows. It is especially useful when debt has different payment patterns or when the simple approximation method may not provide a sufficiently accurate estimate.

4. After Tax Cost of Debt Theory

The After Tax Cost of Debt approach recognises that interest expense on debt may provide a tax benefit to the company, subject to applicable tax rules. Since interest is generally deductible for corporate tax purposes under applicable conditions, the effective cost of debt after tax is lower than its pre tax cost. This makes debt financing relatively attractive compared with equity in many situations. However, the actual tax benefit depends on the company’s taxable income and applicable tax provisions. Therefore, after tax cost of debt is widely used in calculating the company’s overall cost of capital.

5. Cost of Irredeemable Debt Theory

For irredeemable or perpetual debt, the company does not have a fixed redemption date. Therefore, the cost of debt is calculated by relating the annual interest payment to the current market price or net proceeds of the debt. Since the principal is not repaid during the life of the instrument, the interest payments continue indefinitely. This method is relatively simple and is suitable for perpetual debentures and similar instruments. The after tax cost can also be calculated when the tax effect of interest is considered.

6. Cost of Redeemable Debt Theory

The Cost of Redeemable Debt approach considers both periodic interest payments and the amount payable when the debt is redeemed. Unlike irredeemable debt, redeemable debt has a specified maturity date. The effective cost therefore depends on the interest payments, redemption value, issue price or net proceeds and maturity period. This approach provides a more realistic estimate of borrowing cost because it considers the complete cash flow pattern of the debt instrument. It is commonly applied to redeemable debentures, bonds and other fixed maturity debt instruments.

Applications of Cost of Debt:

1. Capital Structure Decisions

Cost of debt is an important factor in determining the appropriate mix of debt and equity in a company’s capital structure. Management compares the cost of debt with the cost of equity to identify a suitable financing combination. Debt may be attractive because interest expenses can provide a tax benefit, subject to applicable tax rules. However, excessive borrowing increases financial risk and repayment obligations. Therefore, cost of debt helps management evaluate the benefits and risks of debt financing and select a capital structure that balances financing cost, financial risk and shareholder interests.

2. Capital Budgeting

Cost of debt is used in capital budgeting to assess the financing cost associated with investment projects. When a project is financed through debt, management needs to consider the cost of borrowing while evaluating the project’s expected returns and cash flows. The after tax cost of debt may also be considered where applicable. Cost of debt can form part of the discount rate through the Weighted Average Cost of Capital. Therefore, it helps determine whether the expected returns from an investment are sufficient to cover the cost of funds used for financing the project.

3. Calculation of WACC

Cost of debt is an essential component of the Weighted Average Cost of Capital. WACC combines the costs of different sources of finance according to their proportion in the company’s capital structure. The after tax cost of debt is generally used when interest provides a tax benefit. Accurate estimation of debt cost is therefore necessary for calculating WACC correctly. WACC is widely used in investment appraisal and business valuation. Hence, cost of debt directly affects the company’s overall financing cost and influences investment and valuation decisions.

4. Debt Financing Decisions

Cost of debt helps management evaluate whether borrowing is an appropriate source of finance for a particular financial requirement. Before obtaining a loan or issuing bonds, the company can estimate the interest cost, issue expenses and other borrowing charges. Management can then compare the effective cost with alternative sources such as equity and retained earnings. This helps identify the most economical financing option while considering risk and repayment capacity. Therefore, cost of debt provides an important basis for selecting suitable debt instruments and financing arrangements.

5. Company Valuation

Cost of debt is used in company valuation because it contributes to the calculation of the overall discount rate, particularly through WACC. Future operating cash flows of a business may be discounted using WACC to determine their present value. Since debt is one component of the financing structure, its cost affects the overall discount rate. A higher cost of debt may increase WACC and reduce the estimated value of future cash flows. Therefore, accurate estimation of cost of debt is important for business valuation and investment analysis.

6. Loan and Bond Evaluation

Cost of debt helps companies evaluate different loan and bond financing options. Borrowing arrangements may differ in terms of interest rates, maturity periods, issue prices, processing charges and other costs. Management can calculate the effective cost of each alternative rather than comparing only the stated interest rates. This allows the company to identify the financing option that provides funds at a suitable overall cost. Therefore, cost of debt is useful when selecting between different debt instruments and negotiating borrowing arrangements with financial institutions and investors.

7. Financial Risk Management

Cost of debt is relevant to financial risk management because borrowing creates fixed financial obligations such as interest and principal repayment. A company with a high cost of debt may face greater pressure on cash flows, especially when operating performance declines. Management can therefore use cost of debt to evaluate the affordability and risk associated with additional borrowing. Monitoring borrowing costs also helps the company assess whether refinancing or restructuring existing debt may be beneficial. Thus, cost of debt supports decisions aimed at controlling financial risk and maintaining adequate debt servicing capacity.

8. Refinancing Decisions

Cost of debt is useful when a company considers replacing existing debt with new borrowing. Management can compare the cost of existing debt with the cost of new financing after considering interest rates, transaction costs, penalties and other charges. If new debt can reduce the effective financing cost without creating excessive risk, refinancing may improve financial efficiency. However, the complete cash flow impact must be considered before making the decision. Therefore, cost of debt provides an important benchmark for evaluating refinancing opportunities and managing the company’s long term borrowing costs.

9. Dividend and Retention Decisions

Cost of debt can indirectly influence dividend and retained earnings decisions. If borrowing is relatively expensive, management may prefer to use internal funds rather than take additional debt, provided sufficient funds are available. Conversely, when borrowing costs are favourable and the company has profitable investment opportunities, debt may be considered as an additional financing source. Management must also consider the effect of borrowing on financial risk and future cash flows. Therefore, cost of debt helps determine whether internal funds, debt or a combination of financing sources should be used to meet investment requirements.

10. Investment and Financing Planning

Cost of debt supports long term financial planning by helping management estimate future borrowing costs and financing requirements. Companies can use the estimated cost of debt while preparing financial projections, investment plans and capital expenditure budgets. It helps determine the likely cost of financing expansion, acquisition, replacement of assets and other major investments. By considering expected interest rates, tax effects and repayment obligations, management can develop a more realistic financing plan. Therefore, cost of debt is an important input in coordinating investment decisions with the company’s overall financing strategy.

Challenges of Cost of Debt:

1. Fluctuation in Interest Rates

One major challenge in determining the cost of debt is the fluctuation in market interest rates. Companies with variable rate loans may experience changes in interest payments when market rates increase or decrease. Even fixed rate debt may become relatively expensive if market interest rates fall after borrowing. Changes in interest rates therefore affect the actual financing cost and future cash flows of the company. Management must monitor interest rate movements and consider refinancing, hedging or suitable debt structures where appropriate. Hence, changing interest rates make accurate long term estimation of cost of debt difficult.

2. Difficulty in Estimating Effective Cost

The stated interest rate does not always represent the actual cost of debt. Companies may incur processing fees, issue expenses, underwriting charges, discounts, premiums and other borrowing costs. These additional amounts affect the net proceeds received and therefore change the effective cost of borrowing. Calculating the true cost requires consideration of all relevant cash flows throughout the debt’s life. This can become complicated when repayment schedules or interest payments vary. Therefore, management must carefully analyse the complete terms of a debt instrument rather than relying only on its stated interest rate.

3. Tax Rate Changes

The after tax cost of debt depends partly on the applicable tax rate and the tax treatment of interest expenses. Changes in tax laws, tax rates or restrictions on interest deductions can alter the effective cost of borrowing. A company may initially estimate a particular tax benefit, but changes in regulations may reduce or modify that benefit. Differences in the company’s taxable income can also affect the actual usefulness of tax deductions. Therefore, uncertainty regarding future taxation creates challenges when estimating the long term after tax cost of debt.

4. Credit Rating Changes

A company’s credit rating can significantly affect its borrowing cost. Companies with strong credit ratings are generally able to borrow at relatively favourable rates because lenders perceive lower default risk. If the company’s financial position deteriorates, its credit rating may decline and lenders may demand a higher interest rate. This can increase the cost of new borrowing and refinancing. Therefore, changes in creditworthiness create uncertainty in estimating future debt costs. Management must monitor financial performance, debt levels and repayment capacity to maintain a favourable credit position.

5. Debt Maturity Period

The maturity period of debt creates challenges in estimating its cost because longer maturity generally involves greater uncertainty about future interest rates and economic conditions. Long term debt may also carry different interest rates compared with short term borrowing. For redeemable debt, the calculation must consider interest payments, issue price, redemption value and the period until maturity. Changes in market conditions during this period can affect refinancing requirements. Therefore, management must carefully consider maturity structure when estimating and managing the company’s overall cost of debt.

6. Market Conditions

Overall financial market conditions influence the cost at which companies can obtain debt. Economic growth, inflation, monetary policy, liquidity conditions and investor sentiment can affect interest rates and credit spreads. During periods of economic uncertainty or tight liquidity, lenders may demand higher returns for providing funds. Conversely, favourable market conditions may allow companies to borrow at lower rates. Since market conditions can change unexpectedly, estimating future borrowing costs can be difficult. Therefore, management must consider both current market conditions and possible future changes while planning debt financing.

7. Credit Risk

Credit risk represents the possibility that a borrower may fail to meet its interest or principal repayment obligations. Lenders consider the financial strength, profitability, cash flow position and existing debt of the company when determining the interest rate. Companies perceived as having higher default risk may have to pay higher interest rates, increasing their cost of debt. Changes in business performance can also affect perceived credit risk over time. Therefore, accurately estimating cost of debt requires careful assessment of the company’s creditworthiness and ability to service its financial obligations.

8. Complex Debt Instruments

Modern companies may use various debt instruments with different interest structures, conversion features, repayment terms and embedded options. Bonds, convertible debentures, floating rate loans and other instruments may require different methods for calculating their effective cost. The presence of discounts, premiums, transaction costs and special repayment conditions can make calculations more complicated. Management must carefully identify all relevant cash flows before estimating the cost of such instruments. Therefore, the complexity of debt contracts can make accurate measurement and comparison of borrowing costs difficult.

9. Refinancing Risk

Refinancing risk arises when a company needs to replace existing debt with new borrowing after maturity. The future cost of refinancing may be higher than the original borrowing cost because market interest rates, credit conditions or the company’s financial position may have changed. This creates uncertainty regarding future financing expenses. A company may also face difficulty obtaining new funds during adverse market conditions. Therefore, management should consider refinancing requirements when evaluating the cost of long term debt and avoid relying solely on the current borrowing rate.

10. Excessive Dependence on Debt

Excessive dependence on debt can increase financial risk and indirectly raise the company’s cost of borrowing. As debt levels increase, lenders may perceive greater risk of financial distress and demand higher interest rates. Higher debt also creates larger fixed payment obligations, which can place pressure on cash flows during periods of weak profitability. Although debt may provide tax benefits, excessive borrowing can reduce financial flexibility. Therefore, management must balance the potential advantages of debt financing with its effect on credit risk, repayment capacity and the overall cost of capital.

Cost of Preference Shares

Cost of Preference Share Capital: An amount paid by company as dividend to preference shareholder is known as Cost of Preference Share Capital.

Preference share is a small unit of a company’s capital which bears fixed rate of dividend and holder of it gets dividend when company earn profit. Dividend payable is not a tax deductible amount. So, there is no tax adjustments required for comparing with cost of debt.

Formula for Cost of Preference Share:

Irredeemable Preference Share

Redeemable Preference Share

Kp = Dp/NP

Kp = Dp+((RV-NP)/n )/ (RV+NP)/2

Where,

Kp = Cost of Preference Share

Dp = Dividend on preference share

NP = Net proceeds from issue of preference share

(Issue price – Flotation cost)

RV = Redemption Value

N = Period of preference share

Example: A preference share issues at 12% worth Rs 60,000 at 5% discount and after 6 years it redeem at 10% premium. The flotation cost is 5% and tax rate is 20%. Find out the cost of preference share capital.

Solution:

Dividend on preference share (Dp) = 60,000*12/100 = Rs.7200

Discount = 60,000*5/100 = Rs.3000

Flotation Cost = 60,000*5/100 = Rs.3000

Net Proceeds (NP) = Rs. (60,000-3000-3000) = Rs. 54,000

Premium amount = 60,000*10/100 =Rs. 6000

Redemption Value = Rs. (60,000+6000) = Rs. 66,000

Kp = Dp+ ((RV-NP)/n)/ (RV+NP)/2

= 7200+ ((66,000-54,000)/6) / (66,000+54,000)/2

= 9200/60,000

= 15.33%

error: Content is protected !!